

Why Tax Efficiency Matters in Retirement
Most professionals and business owners spend decades focused on growing their assets. But once retirement begins, the real question quietly shifts from “How much have I saved?” to “How much of this can I actually use, year after year, without unpleasant surprises?”
The answer is rarely determined by investment performance alone. It is often determined by taxes, timing, and how income is structured once paychecks stop.
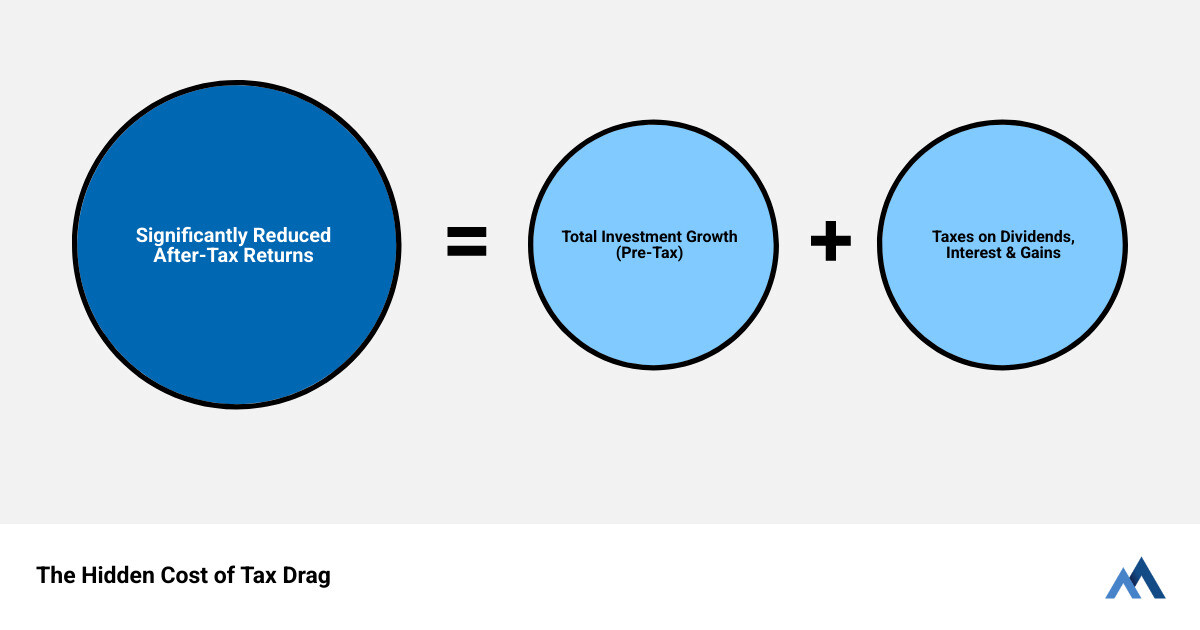
Tax efficient investing in retirement is the discipline of strategically managing where you hold assets and when you withdraw them to minimize the taxes you pay over your lifetime. Without a plan, the cumulative effect of taxes on dividends, interest, capital gains, and withdrawals can significantly reduce your resources.
The challenge also includes navigating how Required Minimum Distributions or other income sources might push you into higher tax brackets or trigger higher Medicare premiums, reducing your control and flexibility.
Who This Guide Is For
This guide is for established professionals, executives, and business owners in areas like Charlottesville and Richmond who have built significant assets across different types of accounts—such as taxable brokerage accounts, 401(k)s, and IRAs. You are now looking to transition from accumulating wealth to distributing it in the most durable, tax-efficient way possible.
You May Be Thinking About Tax Efficiency If:
- You have savings in multiple accounts but lack a clear, coordinated plan for which to draw from first.
- You are concerned about how future income sources, like Social Security and Required Minimum Distributions (RMDs), will impact your overall tax bill.
- You wonder if there are disciplined ways to reduce taxes on your investment portfolio without taking on unnecessary risk or complexity.
Why a Tax-Efficient Withdrawal Strategy Matters
A thoughtful withdrawal plan is not about chasing loopholes; it is a fundamental part of supporting your financial stability. We often see tax inefficiencies surface during specific transition points: the first few years after retiring, the start of Social Security, and the onset of Required Minimum Distributions. These moments tend to stack income sources together, sometimes unintentionally, reducing flexibility and increasing lifetime tax drag. Planning ahead for these transitions is where tax efficiency becomes most valuable.
If this raises questions, we’re happy to talk through what makes sense for your situation.
Core Principles of Tax-Smart Retirement Investing
Experienced advisors approach tax efficiency not as a collection of year-end tactics, but as a core discipline integrated into your long-term retirement planning. The goal is to manage the timing, character, and location of your income to minimize taxes over the full course of your retirement. This rests on three foundational ideas:
- Tax Diversification: Holding assets in different account types (taxable, tax-deferred, tax-free) to provide flexibility as your needs and tax laws change.
- Asset Location: Intentionally placing investments in the accounts where they will receive the most favorable tax treatment.
- Strategic Decumulation: Thoughtfully sequencing withdrawals from your various accounts to create a smooth, tax-optimized income stream.
Practical Considerations for Your Withdrawal Strategy
This is where principles are put into practice. It requires a clear understanding of your assets, the tax rules that govern them, and a disciplined plan for drawing income.
Understanding Your Investment Income and Its Tax Treatment
Not all investment returns are taxed equally. Interest from bonds is typically taxed as ordinary income, while qualified dividends and long-term capital gains often receive more favorable tax rates. Understanding these distinctions is the first step in managing your tax liability.
In broad terms, you will usually see your investment income fall into a few categories:
- Interest income: Common from bonds and savings vehicles, generally taxed at ordinary income rates.
- Qualified dividends: Dividends that meet certain holding and issuer requirements and may be taxed at long-term capital gains rates. You can find a straightforward definition in resources such as IRS Publication 550.
- Long-term capital gains: Gains on assets held for more than one year, often taxed at preferential rates.
- Short-term capital gains: Gains on assets held for one year or less, typically taxed as ordinary income.
- Net Investment Income Tax (NIIT): An additional tax that may apply if your income exceeds certain thresholds. The IRS provides an overview at Net Investment Income Tax.
Understanding where your income falls among these categories helps you and your advisor decide which accounts to draw from, and when, in order to manage your overall tax picture.
The Role of Asset Location in tax efficient investing in retirement
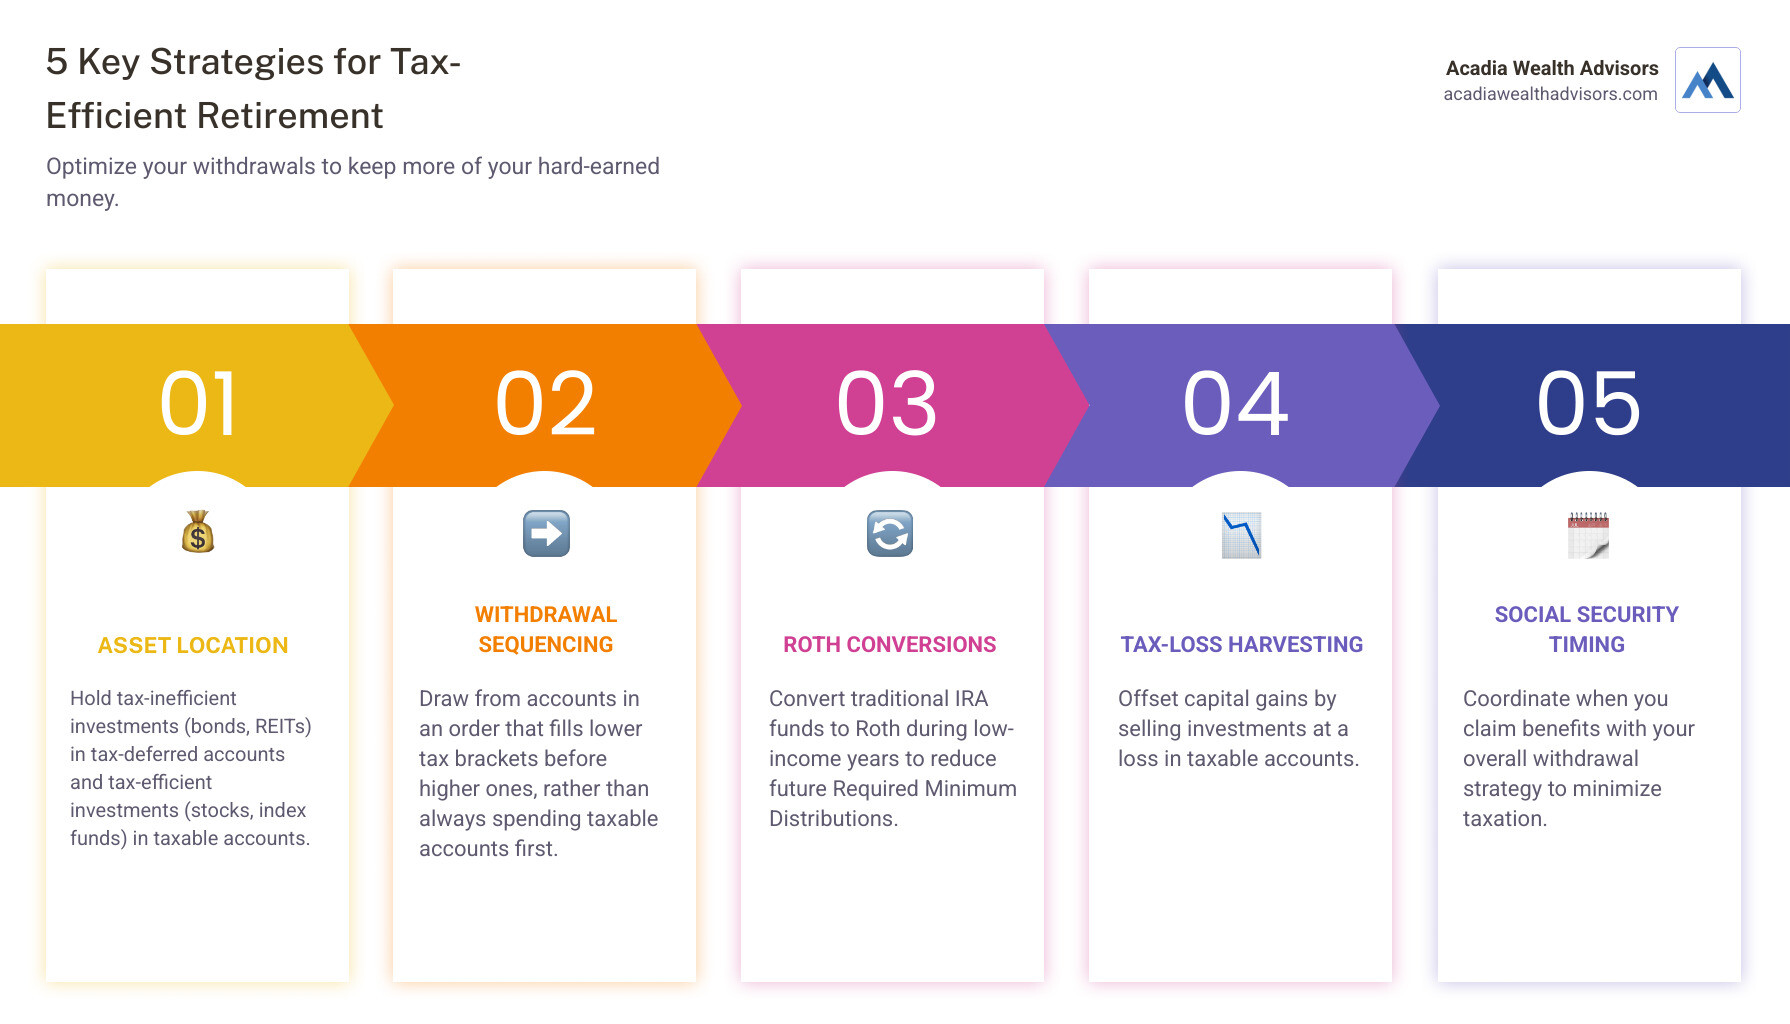
Asset location involves placing your investments in the right accounts to optimize tax outcomes. For example, tax-inefficient assets that generate high annual income, like certain bonds, may be better suited for tax-deferred accounts. Tax-efficient assets, like broad-market index funds, may be appropriate for taxable accounts.
- Taxable accounts: Often a good home for tax-efficient stock index funds or ETFs, municipal bonds (when appropriate), and assets you may want flexible access to.
- Tax-deferred accounts (Traditional IRA/401(k)): Frequently used for investments that generate regular taxable income, such as many bond funds or actively traded strategies, since the income is sheltered until withdrawal.
- Tax-free accounts (Roth IRA/HSA): Well-suited for investments with higher growth potential, since qualified withdrawals are tax-free.
This distinction between what you own (asset allocation) and where you own it (asset location) is a key part of long-term tax efficiency and is consistent with the way many practitioners and researchers describe tax-aware portfolio design.
Creating a Tax-Smart Withdrawal Sequence
The conventional wisdom of spending from taxable accounts first isn’t always the best approach. A more nuanced strategy may involve taking distributions from tax-deferred accounts to “fill up” lower tax brackets early in retirement, or using Roth conversions to manage future RMDs. This is particularly relevant for those with significant assets.
Some of the practical issues to weigh include:
- The size and timing of Required Minimum Distributions (RMDs).
- When you plan to start Social Security, and how that income will interact with other withdrawals.
- How much room you have in current tax brackets to take additional distributions or do Roth conversions without pushing yourself into higher brackets.
Navigating these details can feel complex, but a well-structured plan brings clarity and confidence. The goal is a steady, repeatable process, not a perfect prediction of the future.
Key Strategies for tax efficient investing in retirement
Beyond asset location and withdrawal sequence, several other strategies can improve your plan.
Tax-Loss Harvesting in Your Taxable Accounts
This strategy involves selling investments in your taxable portfolio at a loss to offset capital gains realized from other investments. When done systematically, it can help manage your tax bill while keeping your portfolio aligned with your long-term allocation goals. For instance, a loss from selling one investment can be used to offset a gain realized from another. If you have more losses than gains in a year, a portion may be used to offset ordinary income, with any remaining losses carried forward to future years. This requires year-round discipline and careful attention to rules like the wash sale rule, which prevents you from repurchasing a substantially identical security shortly after selling it at a loss.
Using Roth Accounts and Conversions Strategically
Roth accounts offer tax-free growth and tax-free withdrawals in retirement, making them a valuable tool for tax efficient investing in retirement. For some, especially business owners in Alexandria or Roanoke expecting significant future income or RMDs, converting traditional IRA funds to a Roth IRA can be a prudent long-term move. This involves paying taxes on the converted amount now, but then all future qualified withdrawals are tax-free. This strategy can be particularly effective during years when your income is temporarily lower, such as a sabbatical, or in the gap between retirement and claiming Social Security. It can reduce your future RMDs and create a valuable source of tax-free income that won’t trigger higher Medicare premiums or Social Security taxation. Managing wealth as a business owner has its own set of considerations.
Integrating Charitable and Estate Planning Goals
Your tax strategy should align with your legacy goals. Techniques like donating appreciated securities directly to a qualified public charity can provide a double tax benefit: you avoid paying capital gains tax on the appreciation, and you can claim a charitable deduction for the fair market value of the securities. Another strategy for those who are of eligible age is a Qualified Charitable Distribution (QCD) directly from an IRA, which counts toward your RMD but is excluded from your taxable income. For those planning a more extensive legacy, a Donor-Advised Fund (DAF) can allow you to make a charitable contribution, receive an immediate tax deduction, and then recommend grants to charities over time. These strategies are key components of both estate planning and wealth transfer and legacy planning. They allow you to support causes you care about while optimizing your tax position, especially when considering the step-up in basis for inherited assets.
A Framework for Your Retirement Income Plan
- Inventory Your Assets: Create a clear map of all your accounts, categorizing them by tax type: taxable, tax-deferred, and tax-free. This provides a comprehensive overview of your resources.
- Project Your Income Needs: Establish a realistic budget for your annual spending requirements in retirement, accounting for both essential and discretionary expenses.
- Model Withdrawal Scenarios: Work with an advisor to project the long-term tax impact of different withdrawal sequences and Roth conversion strategies. This helps illustrate potential outcomes and identify the most efficient path.
- Coordinate with Social Security: Decide on a claiming age that complements your withdrawal plan and minimizes taxes on your benefits. For example, delaying Social Security to the maximum age can increase your annual benefit, but it also impacts your early retirement income planning.
- Review and Adjust Annually: A financial plan is a living document. It should be reviewed regularly to adapt to changes in your life, the market, and tax law, ensuring your strategy remains optimal.
Frequently Asked Questions About Tax-Efficient Withdrawals
What is the best order to withdraw money from my retirement accounts?
While the common advice is “taxable, tax-deferred, then tax-free,” the optimal sequence depends on your specific situation. For some, it may be better to draw from tax-deferred accounts early to take advantage of low tax brackets before RMDs and Social Security begin. This can be especially true if you anticipate being in a higher tax bracket later in retirement due to RMDs or other income sources. The goal is to smooth out your taxable income over your entire retirement.
Should I do a Roth conversion, and when is the best time?
A Roth conversion can be a valuable tool, especially in years when your income is lower, such as the gap between retirement and starting Social Security. It allows you to pay taxes now, presumably at a lower rate, in exchange for tax-free withdrawals later and a reduction in future RMDs. This strategy can be particularly beneficial if you expect tax rates to be higher in the future or if you want to leave a tax-free inheritance to your beneficiaries.
How can I reduce my Required Minimum Distributions (RMDs)?
Strategies to reduce future RMDs include making Qualified Charitable Distributions (QCDs) directly from your IRA if you are over the eligible age. These distributions count towards your RMD but are excluded from your taxable income. Another effective strategy is to execute Roth conversions in the years before RMDs begin. By moving funds from a Traditional IRA to a Roth IRA, those assets are no longer subject to RMDs.
How does my Social Security claiming age affect my taxes?
Delaying Social Security can increase your monthly benefit, but it also creates a window of time in your early retirement years where your taxable income may be lower. This can be a good time to execute Roth conversions at a more favorable tax rate. Conversely, claiming early provides immediate income but can reduce your annual benefit and potentially increase the taxable portion of your Social Security benefits if your other income is high, a phenomenon sometimes called the “tax torpedo.”
Can I still use tax-loss harvesting once I’m retired?
Yes. Tax-loss harvesting remains a valuable strategy in retirement for any assets held in taxable brokerage accounts. It can be used to offset capital gains from portfolio rebalancing or from selling assets to generate income. This technique helps manage your annual tax bill without necessarily changing your long-term investment strategy.
Gaining Clarity for the Years Ahead
Building a tax efficient investing in retirement income plan is one of the effective ways to protect the wealth you’ve worked a lifetime to create. It can provide stability and control in a phase of life where both are paramount. While the details can feel intricate, the objective is straightforward: keep more of what you have worked to build, and maintain flexibility as life evolves. A thoughtful, tax-aware strategy does not eliminate uncertainty, but it gives you control over the factors you can influence. That clarity is often what allows retirement plans to endure across decades, not just markets..
If you’d like a second opinion or a clearer framework, we’re available to help.