

Why Retirement Income Investing Requires a Different Mindset
Retirement income investing represents a fundamental shift in how you approach your portfolio. After decades of accumulation, you’re now tasked with converting savings into a reliable income stream that must sustain you for what could be 20 to 30 years or more.
Quick Answer: Core Elements of Retirement Income Investing
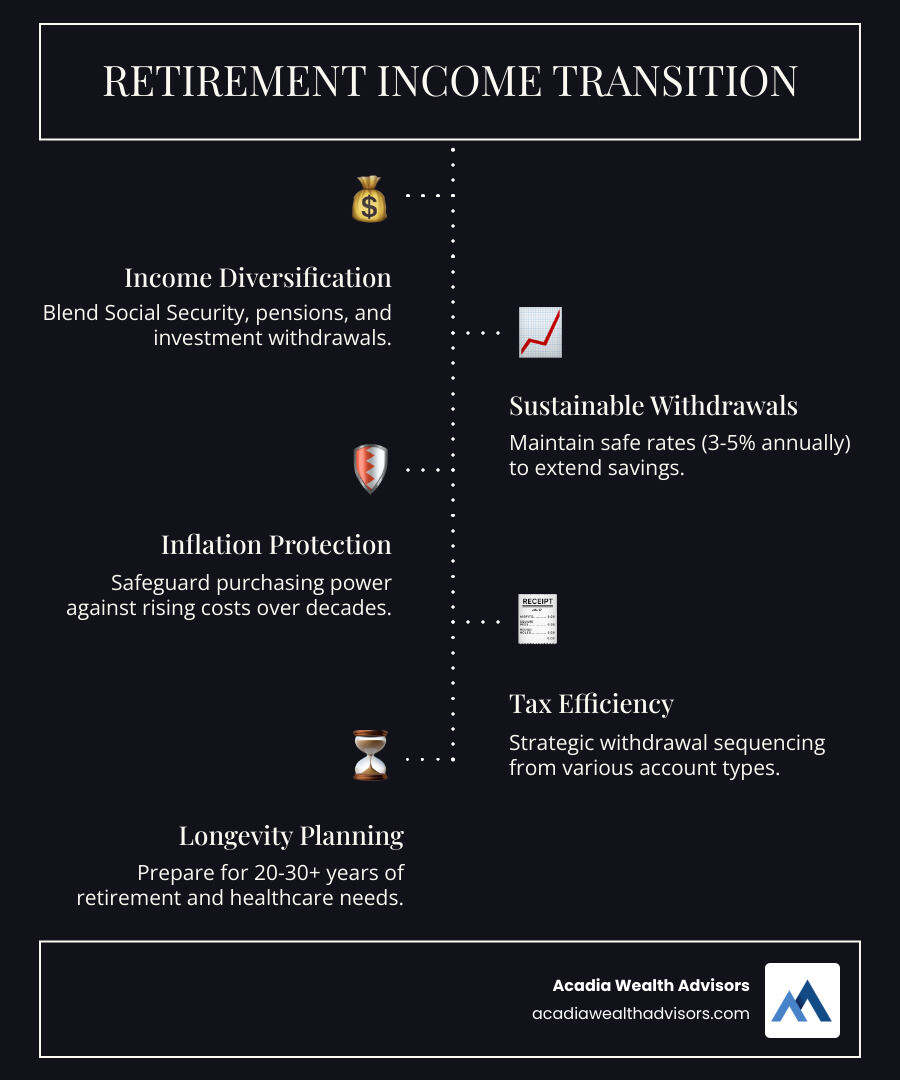
- Diversify income sources – Social Security, investment withdrawals, potential pensions, and other streams
- Balance growth and stability – Maintain equity exposure for long-term growth while preserving capital for near-term needs
- Manage withdrawal strategy – commonly referenced withdrawal ranges
- Account for longevity – Plan for extended life expectancy and rising healthcare costs
- Optimize tax efficiency – Sequence withdrawals from taxable, tax-deferred, and tax-free accounts strategically
This transition from saving to spending is more than a mathematical exercise. It’s a psychological shift that requires both discipline and flexibility. You’re no longer asking “how much can I save?” but rather “how much can I safely withdraw?” The timing of market returns becomes critical, inflation poses a real threat to purchasing power, and tax efficiency takes on new importance.
For business owners in Charlottesville and throughout Virginia, this often means planning for income beyond the business itself. Many professionals we work with have successfully built wealth through their companies but haven’t yet structured a systematic approach to convert that wealth into sustainable retirement cash flow.
I’m Frank Gristina, Managing Partner at Acadia Wealth Advisors, and I’ve spent more than 25 years helping clients steer complex investment decisions, including developing disciplined strategies for retirement income investing. My approach emphasizes aligning your portfolio with your actual spending needs while maintaining the flexibility to adapt as markets and circumstances change.
The strategies that follow represent principles drawn from decades of market cycles, research into withdrawal methodologies, and real-world experience guiding retirees through both calm periods and volatility. The goal is clarity and confidence, not perfection.
Retirement income investing vocabulary:
Foundations of Your Retirement Income Plan
Building a robust retirement income investing plan begins with a clear understanding of your financial landscape. This involves not only identifying your various income sources but also establishing a solid foundation to protect your accumulated wealth. Diversification, in this context, extends beyond just investments to encompass your entire income stream.
For business owners in Charlottesville, Roanoke, and across Virginia, planning for income after stepping away from the business is a critical step. It requires transitioning from a focus on business growth to personal financial stability. This often involves ensuring that various income streams are in place and working in concert to support your desired lifestyle.
Understanding Your Primary Income Sources
Your retirement income will likely be a mosaic of different sources, each with its own characteristics and implications. Beyond your investment portfolio, these typically include Social Security, and for some, pension benefits.
Social Security, for instance, represents a foundational layer of income for many. The timing of when you begin claiming these benefits can significantly impact the total amount you receive over your lifetime. While claiming benefits early might seem appealing, delaying them, often until a later age, can result in substantially larger monthly payments. This decision can be particularly impactful for married couples, where coordinating claims can optimize lifetime benefits for both spouses.
For those fortunate enough to have pension benefits, understanding the payout options is crucial. You might face a choice between a lump sum payment or an annuity that provides regular income. Each option carries distinct advantages and disadvantages, including tax implications and the level of guaranteed income. We often help clients evaluate these choices, considering factors like your health, other income sources, and legacy goals.
Your primary income sources often blend guaranteed income streams, where an outside entity promises a specified amount, with variable income derived from your personal savings and investments. The art of retirement income investing lies in blending these to create a reliable and sustainable financial future.
More info about Retirement Planning.
The Importance of a Cash Reserve
One of the most valuable components of any retirement income investing strategy is a dedicated cash reserve. This isn’t just about having accessible funds; it’s a strategic buffer designed to shield your long-term investments from short-term market fluctuations and unexpected expenses.
Think of your cash reserve as a financial “rainy day” fund specifically custom for retirement. It provides liquidity, ensuring you don’t have to sell investments during market downturns to cover your immediate living expenses. Having several months’ worth, or even a year’s worth, of essential expenses held in low-risk, easily accessible accounts can offer significant peace of mind.
This reserve allows your growth-oriented assets time to recover from market volatility, preventing you from locking in losses. It’s a fundamental risk management tool that helps maintain the integrity of your overall portfolio, especially during the early years of retirement when the sequence of investment returns can have a disproportionate impact.
Core Strategies for Retirement Income Investing
The central challenge in retirement income investing is figuring out how to draw a consistent income from your accumulated capital without depleting it too quickly. This isn’t a one-size-fits-all problem, and we often see clients in the Richmond area, and across Virginia, weigh different philosophies based on their unique circumstances and risk comfort. There are generally three main approaches: the total return approach, the income-centric approach, and a hybrid model.

The Total Return Approach
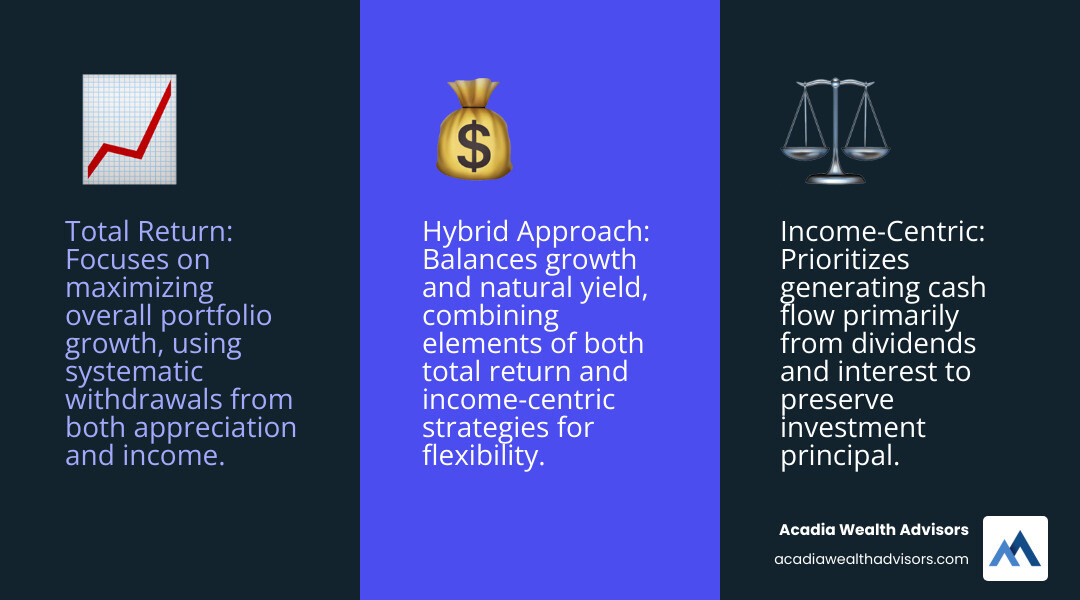
The total return approach focuses on maximizing the overall growth of your investment portfolio, encompassing both capital appreciation and any dividends or interest generated. Instead of relying solely on investment income, you systematically withdraw a portion of your portfolio’s total value each year, regardless of whether it comes from dividends, interest, or selling appreciated assets.
A key benefit of this strategy is its flexibility. It allows your portfolio to be constructed without artificial income constraints, aiming for a robust blend of growth potential. When one part of your portfolio performs well, you can trim those appreciated assets, effectively using rebalancing as an income source. This can be particularly advantageous in varying market conditions.
However, this approach requires careful management to mitigate sequence of returns risk—the danger that poor investment returns early in retirement could disproportionately deplete your capital. A well-defined withdrawal strategy and periodic adjustments are essential to ensure your savings endure throughout your retirement years.
The Income-Centric Approach
In contrast, an income-centric approach prioritizes generating cash flow primarily from the dividends and interest produced by your investments. The goal is often to live off this natural yield, preserving the principal of your investment portfolio. This can be appealing for those who value the psychological comfort of not “touching” their core savings.
This strategy often involves a heavier allocation to dividend-paying stocks, bonds, and other income-producing securities. The attraction is a consistent stream of income that may feel more predictable than relying on capital gains.
However, this approach is not without its considerations. The income generated can be subject to interest rate risk, where rising rates might devalue existing bonds, or inflation risk, where the purchasing power of a fixed income stream erodes over time. Additionally, relying heavily on dividends can expose you to the risk of companies cutting or reducing their payouts during challenging economic periods.
The Hybrid Approach: A Balanced Framework for Retirement Income Investing
For many, a hybrid approach offers a balanced and flexible framework for retirement income investing. This strategy combines elements of both the total return and income-centric models, seeking to leverage the strengths of each while mitigating their respective weaknesses.
A hybrid strategy typically involves owning a mix of income-producing securities to provide a baseline cash flow, while also constructing the broader portfolio for total return. This means you might use the natural income distributions (dividends, interest) to cover a portion of your living expenses. If additional funds are needed, you then strategically trim appreciated holdings from your growth-oriented assets.
One popular way to implement a hybrid strategy is through a “bucket” approach. This involves segmenting your assets into different “buckets” based on when you anticipate needing the funds. For instance, you might allocate liquid assets for near-term needs, fixed income for mid-term goals, and equities for long-term growth. Income generated from these various buckets can then be used to replenish the more liquid portions as needed. This approach offers both a degree of income certainty and the potential for long-term growth, providing flexibility and adaptability in different market environments.
Building Your Income Portfolio: Key Asset Classes
Once you’ve considered your overarching strategy for retirement income investing, the next step is to populate your portfolio with asset classes that align with your goals. A well-diversified portfolio is crucial, balancing risk and reward while ensuring different investments play distinct roles in generating income and growth.
Dividend-Paying Stocks and Equity Funds
For many retirees, dividend-paying stocks and equity funds are an essential component of their income portfolio. They serve a dual role: providing a regular income stream through dividends and offering the potential for capital appreciation, which can help your portfolio grow and combat the effects of inflation over time.
While dividends provide direct cash flow, the growth potential of equities is vital for long retirements, which can span many decades. This growth helps ensure that your income stream can keep pace with rising living costs. When selecting dividend-paying investments, we emphasize focusing on companies with a history of consistent and growing dividends, rather than simply chasing the highest yields, which can sometimes signal higher risk. Like all equity investments, dividend stocks carry market risk, meaning their value can fluctuate. However, their role in providing both income and growth makes them a valuable consideration for a balanced retirement portfolio.
Bonds and Fixed-Income Securities
Bonds and fixed-income securities are traditionally valued for their ability to provide stable income and contribute to capital preservation. They can act as a ballast in a diversified portfolio, offering a predictable stream of interest payments and generally exhibiting lower volatility than stocks.
One common strategy for utilizing bonds in retirement is creating a bond ladder. This involves purchasing bonds with staggered maturity dates. As each bond matures, the principal can be reinvested into a new bond at the longer end of the ladder, helping to manage interest rate risk and providing a continuous flow of funds.
When considering fixed income, it’s important to be mindful of interest rate risk (the potential for bond prices to fall when interest rates rise) and credit quality (the likelihood of the issuer repaying the debt). Diversifying your fixed-income holdings across different types of bonds and issuers can help mitigate these risks.
Other Income-Generating Assets: REITs and Annuities
Beyond traditional stocks and bonds, other asset classes can play a role in generating retirement income.
Real Estate Investment Trusts (REITs), for example, offer a way to invest in real estate without directly owning physical properties. REITs typically own and operate income-producing real estate, such as apartment complexes, shopping centers, or office buildings, and are required to distribute a significant portion of their taxable income to shareholders as dividends. This can provide a stream of income and diversification from traditional equity markets. However, REITs are subject to market fluctuations and real estate market risks.
Annuities, which are insurance contracts, are another option for those seeking guaranteed income streams. They can convert a lump sum of money into a series of payments over a specified period or for the rest of your life. While annuities can provide a sense of security by offering income you cannot outlive, they often come with complexities, various features, and associated costs that require careful evaluation. We help clients understand the suitability of annuities for their specific goals, considering factors like their need for guaranteed income versus flexibility and potential for growth.
Managing Your Plan: Withdrawal, Risk, and Tax Strategies
An effective retirement income investing plan is not static; it’s a dynamic framework that requires ongoing management and adaptation. Your life circumstances, market conditions, and economic environment will inevitably change, necessitating regular reviews and adjustments to ensure your strategy remains aligned with your objectives.
At Acadia Wealth Advisors, we emphasize that aligning your strategy with your life is paramount. This means your financial plan should evolve as you do, whether that involves adjusting spending in response to market performance or adapting to unforeseen healthcare needs. Our approach as a Financial Advisor in Charlottesville VA focuses on proactive guidance and thoughtful adjustments.
Developing a Sustainable Withdrawal Strategy
The cornerstone of managing your retirement income is establishing a sustainable withdrawal strategy. This involves determining a prudent initial percentage of your portfolio to withdraw annually and then adjusting that amount over time. The goal is to ensure your savings last throughout your retirement years without running out of funds.
A common principle is to start with a considered initial withdrawal percentage and then adapt subsequent withdrawals based on market performance and inflation. For instance, in years of strong market performance, you might maintain or slightly increase your withdrawal, while in challenging market periods, a temporary reduction could be prudent to preserve capital. This dynamic approach helps avoid the premature depletion of your nest egg, especially important in the face of market volatility early in retirement.
Mitigating Key Risks in Retirement Income Investing
Several risks can challenge the longevity of your retirement income, and a robust plan addresses each proactively.
- Longevity Risk: With individuals living longer than ever, planning for a retirement that could span many decades is essential. This means your income strategy must be designed for durability, ensuring your funds don’t run out prematurely.
- Inflation’s Impact: Inflation erodes purchasing power over time. What seems like a comfortable income today may buy significantly less in the future. Your portfolio needs components that can grow sufficiently to help your income keep pace with rising costs.
- Market Volatility and Sequence Risk: The order in which market returns occur can have a profound effect on your portfolio’s longevity. Poor returns early in retirement, combined with withdrawals, can severely diminish your capital. A well-structured asset allocation and flexible withdrawal strategy are key to managing this “sequence of returns” risk.
Incorporating Tax Efficiency
Tax efficiency is a critical,, aspect of retirement income investing. How you choose to withdraw funds from different account types can significantly impact your net income and the overall longevity of your portfolio.
A strategic approach often involves what’s known as asset location—deciding which types of investments to hold in taxable versus tax-advantaged accounts. Equally important is the withdrawal sequencing: generally, it can be tax-efficient to draw from taxable accounts first, then tax-deferred accounts (like traditional IRAs or 401(k)s), and finally, tax-free accounts (such as Roth IRAs). This sequencing helps manage your taxable income each year and can minimize your overall tax burden throughout retirement.
Additionally, understanding Required Minimum Distributions (RMDs) is crucial for those with tax-deferred accounts in later retirement years. These are mandatory withdrawals that begin at a certain age, and failing to take them can result in significant penalties. We guide clients through these complexities, helping them steer regulations like the Net Investment Income Tax FAQs from the IRS to optimize their tax strategy.
Frequently Asked Questions about Retirement Income Investing
What is the best way to generate income in retirement?
There is no single “best” way; the optimal strategy depends on your personal financial situation, risk tolerance, and income needs. It typically involves a diversified approach, blending guaranteed income sources like Social Security with a well-structured investment portfolio that balances growth and income generation.
How can I make my retirement savings last for 30 years or more?
Making savings last requires a disciplined approach that includes a sustainable withdrawal strategy, managing investment risk, accounting for inflation, and maintaining flexibility to adjust your plan as market conditions and personal circumstances change. A focus on total return and tax efficiency is also crucial.
Should I still own stocks in retirement?
For most retirees, maintaining an allocation to stocks is essential. Given increasing life expectancies, the growth potential of equities is often necessary to help your income stream keep pace with inflation over a multi-decade retirement. The key is to balance this growth potential with more stable, income-producing assets.
Conclusion: Creating a Durable and Confident Retirement
Navigating retirement income investing requires a thoughtful, disciplined, and adaptable approach. The core principles remain consistent: diversify your income sources, implement a disciplined withdrawal strategy, and dynamically manage your plan to account for life’s inevitable changes. The goal is to establish a clear, durable financial plan that provides confidence and peace of mind throughout your golden years.
We understand that the complexities of converting wealth into a sustainable income stream can feel daunting. That’s why the value of professional guidance is so significant. At Acadia Wealth Advisors, we help clients in Virginia, from Alexandria to Richmond, and Charlottesville to Roanoke, build personalized, data-driven strategies for their long-term goals. Our focus is on providing the clarity and stability you need to enjoy the retirement you’ve envisioned.