

Why Your Retirement Savings Deserve a Thoughtful Drawdown Plan
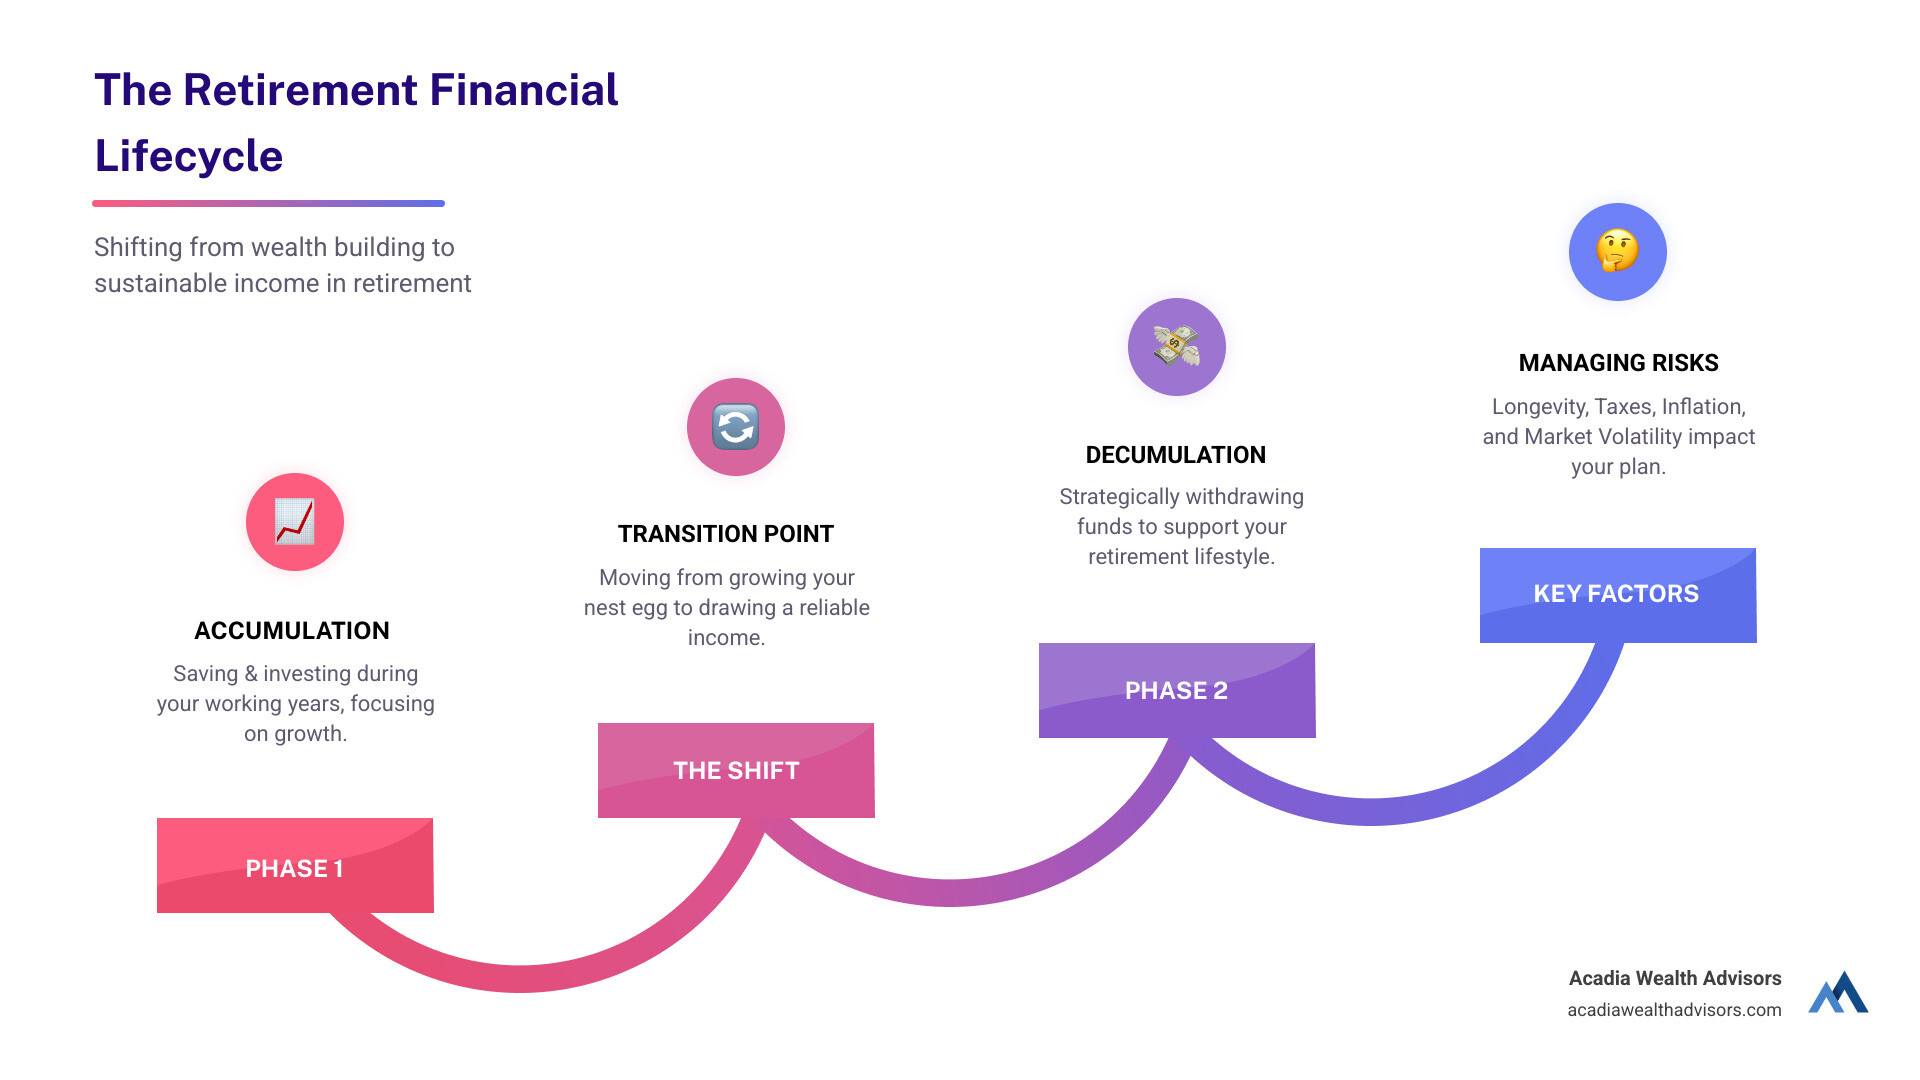
For years, you’ve focused on building your savings—steadily preparing for the future. Now, as you approach or enter retirement, the focus shifts from growing your nest egg to drawing a sustainable income from it. This transition brings an important question: How do you turn your savings into a reliable income stream that can last for the rest of your life?
Retirement drawdown strategies are methods for converting your savings into income. Common approaches include the 4% Rule, the Bucket Strategy, Proportional Withdrawals, and Dynamic Withdrawals. Each has trade-offs, and the right choice depends on your income needs, risk tolerance, and tax situation.
The challenge is real. Your savings may need to support you for 20 to 30 years—or longer. During that time, you’ll face market volatility, inflation, and changing tax laws. Unlike the accumulation phase, where time worked in your favor, the drawdown phase requires a different kind of planning. Early losses can have lasting impacts, and inflation steadily erodes purchasing power.
There’s no single “right” way to withdraw from your savings. But there are thoughtful, principle-based strategies that can help you manage these risks and create a plan that aligns with your goals.
As Frank Gristina, I’ve guided families through more than 25 years of market cycles, helping them build personalized retirement drawdown strategies. At Acadia, we believe retirement planning is about creating clarity and confidence—not following a one-size-fits-all formula.
Who This Is For & How This Guide Helps
This guide is for individuals and families in Virginia—whether you’re in Charlottesville, Richmond, Northern Virginia, or Albemarle County—who are within 5 to 10 years of retirement or have recently retired. It’s for professionals, business owners, and couples who are thoughtfully planning their next chapter.
You’ve worked hard to build your savings. Now you’re facing a different kind of challenge: turning those savings into income that can support you for the rest of your life.
Maybe you’re unsure if your savings will last through 20 or 30 years of retirement. Perhaps you’re wondering how to turn your 401(k) or IRA into a steady “paycheck.” Or you might be concerned about how market changes or inflation might affect your income.
These are the questions that keep people up at night—not because you’ve done anything wrong, but because this transition from saving to spending is genuinely complex.
This guide offers a calm, clear framework for understanding retirement drawdown strategies. Our goal is to help you move from uncertainty to clarity, so you can build a plan that supports your life and long-term goals. It’s about navigating market cycles, taxes, inflation, and longevity with a steady, principled approach.
Why Retirement Drawdown Is a Unique Challenge
For decades, your financial life followed a familiar rhythm: you earned, you saved, you watched your investments grow. When markets dipped, you had time on your side to recover and keep contributing.
Retirement changes everything.
The moment you start withdrawing from your savings, you’re playing a different game entirely. The rules that served you well during your working years don’t necessarily apply anymore. In fact, some of them work against you.
During the accumulation phase, market volatility was almost a friend, giving you the chance to buy investments at lower prices. In retirement, those same downturns can be devastating if they happen at the wrong time. This is what financial planners call “sequence of returns risk,” and it’s one of the most significant threats to a long retirement.
If the market drops significantly early in your retirement, you are forced to sell more investments at depressed prices to cover your living expenses. This locks in losses and permanently reduces the capital you have working for you. Even when the market recovers, your portfolio may never fully catch up.
And that’s just one challenge. Inflation quietly erodes your purchasing power every single year. What feels comfortable today may feel tight in a decade. Then there are taxes. The decisions you make about which accounts to draw from first—your taxable brokerage account, your Traditional IRA, your Roth IRA—can mean the difference between keeping more of your money and unnecessarily enriching the IRS.
Finally, there’s the biggest unknown: how long will you need your money to last? A thoughtful retirement drawdown strategy helps you steer all of this with confidence. It gives you a framework for making withdrawal decisions that account for market risk, inflation, taxes, and longevity—not just today, but across decades. It’s not about predicting the future. It’s about building a plan flexible enough to adapt to whatever comes.
Core Retirement Drawdown Strategies: Finding Your Approach
Choosing how to withdraw your savings is one of the most important financial decisions you’ll make. The right retirement drawdown strategy depends on your financial situation, comfort with market volatility, and personal goals. Some retirees value simplicity, while others prefer flexibility or tax efficiency. Understanding your options helps you make an informed choice.
Here’s how the primary strategies compare:
| Strategy | Flexibility | Complexity | Market Sensitivity | Key Benefit |
|---|---|---|---|---|
| 4% Rule | Low (fixed percentage) | Low | Moderate (assumes consistent market returns) | Simplicity, historical track record |
| Bucket Strategy | Moderate (can adjust bucket allocations) | Moderate | Low (short-term cash insulated from market swings) | Psychological comfort, risk management |
| Proportional Withdrawals | Moderate (can adjust account mix) | Moderate | High (draws from all accounts, including equities) | Tax efficiency, smoothed tax liability |
| Dynamic Withdrawals | High (adjusts to market and personal needs) | High (requires active management) | High (directly responds to market performance) | Longevity, adapts to changing circumstances |
Have questions? We’re here to help you find clarity and move forward with confidence. Ready to talk through your financial goals? Schedule a calm, pressure-free conversation with Acadia Wealth Advisors.
The 4% Rule: A Simple Starting Point
The 4% rule is a straightforward guideline: withdraw 4% of your portfolio in your first year of retirement, then adjust that dollar amount for inflation each year after. Developed in the 1990s based on historical data, it was designed to make savings last for 30 years.
Its appeal is its simplicity, providing a predictable income stream. However, the 4% rule has limitations. It doesn’t account for today’s lower interest rate environment, longer life expectancies, or the danger of poor market performance early in retirement (sequence of returns risk). We view it as a useful starting point for discussion, not a rigid rule.
More info about our approach to retirement planning
The Bucket Strategy: Segmenting Your Savings for Peace of Mind

The bucket strategy divides your savings into different pools based on when you’ll need the money, providing both practical income and psychological security.
- Short-term bucket: Holds 1-3 years of living expenses in safe assets like cash. This protects your immediate income from market swings.
- Mid-term bucket: Covers expenses for the next 4-10 years with conservative investments like bonds, aiming for modest growth with relative stability.
- Long-term bucket: Contains funds for 10+ years out, invested for growth in a diversified portfolio of stocks.
As you spend from the short-term bucket, you periodically refill it from the mid-term bucket, which is in turn refilled from long-term investments—ideally when they have performed well. This helps you avoid selling stocks during a downturn.
Proportional and Total Return Withdrawals: A Holistic View
Proportional withdrawals take a coordinated approach, drawing from your taxable, tax-deferred, and Roth accounts based on their share of your total portfolio. This can smooth your tax liability over your entire retirement.
The total return approach focuses on your portfolio’s overall growth, not just interest and dividends. You withdraw a set percentage of your total portfolio value each year, drawing from whatever combination of accounts makes the most tax sense at that moment.
Both strategies require careful coordination to manage the different tax treatments of each account type. For families in Charlottesville and throughout Virginia with savings across multiple accounts, the complexity can be worth the potential tax savings.
Dynamic Withdrawals: Adjusting to Market Realities
Dynamic retirement drawdown strategies build flexibility directly into your plan. Instead of a fixed withdrawal, you adjust your spending based on portfolio performance. One common approach uses “guardrails,” allowing you to spend more after strong market years and less after declines.
This flexibility helps protect your portfolio during downturns, making your money more likely to last. The trade-off is income variability, so this approach works best for retirees with flexible spending needs. For professionals in Northern Virginia and Richmond comfortable with active engagement, it can be a highly sustainable long-term approach.
More on financial planning for high net worth individuals
Key Factors That Shape Your Withdrawal Plan
A successful drawdown strategy is custom to your unique circumstances. No two retirements are alike, and your plan should reflect your individual goals, lifestyle, and financial landscape in Virginia.
A 4-Step Checklist for Reviewing Your Drawdown Plan:
- Re-evaluate your spending needs: What are your fixed costs versus flexible expenses?
- Account for all income sources: How do Social Security and any pensions cover your essential needs?
- Review your tax situation: What are the tax implications of withdrawing from different accounts?
- Assess your portfolio: Is your investment mix still aligned with your risk tolerance and withdrawal needs?
Planning for Longevity, Taxes, and Other Income
Your plan must account for your entire retirement, which could last 30 years or more. Life expectancy is a crucial factor (you can see averages on the Social Security Administration’s website), and your plan should balance enjoying retirement now with preserving capital for the future.
Deciding when to start Social Security is another key decision. Starting early at 62 reduces your benefit, while delaying to age 70 maximizes it. The right timing depends on your health, other income, and overall plan. Any pension or annuity income also plays a role, providing a stable base to cover essential expenses.
Finally, taxes are an ever-present consideration. Withdrawals from traditional accounts (IRA/401(k)) are taxed as ordinary income, while qualified Roth withdrawals are tax-free. We also consider Virginia state income tax implications to design a tax-efficient withdrawal sequence.
Understanding Required Minimum Distributions (RMDs)
Required Minimum Distributions (RMDs) are mandatory withdrawals from tax-deferred retirement accounts like Traditional IRAs and 401(k)s. The starting age is currently 73, rising to 75 by 2033 for those born in 1960 or later.
RMDs are calculated annually based on your prior year-end account balance and an IRS life expectancy factor. These withdrawals are taxed as ordinary income and must be integrated into your tax planning. Failing to take RMDs can result in significant penalties.
More on wealth transfer and legacy planning
A Thoughtful Approach to Tax-Efficient Retirement Drawdown
Minimizing taxes is a critical part of a sustainable plan. While conventional wisdom suggests a fixed withdrawal order (taxable, then tax-deferred, then tax-free), a more dynamic approach is often better.
We might consider strategically drawing from different account types to “fill” lower tax brackets each year. For example, you might take from a tax-deferred account to use up a low tax bracket or realize gains from a taxable account to take advantage of the 0% long-term capital gains rate.
Strategic Roth conversions can also be powerful, especially in years before RMDs begin. This can reduce your future taxable income and help manage your lifetime tax burden.
More on our estate planning services
Managing Risk and Adapting Your Strategy Over Time
A well-structured plan provides clarity, but its true strength is its ability to adapt. Confidence comes from knowing your strategy can evolve with your life and the markets.
Ready to talk through your financial goals? Schedule a calm, pressure-free conversation with Acadia Wealth Advisors.
Mitigating Key Risks in Retirement
A thoughtful retirement drawdown strategy must address the unique risks of this phase.
Sequence of returns risk is the danger that poor market returns early in retirement can significantly reduce your portfolio’s longevity. Withdrawing funds while investments are down forces you to sell more shares at a lower price, and those shares can’t participate in the eventual recovery. The bucket strategy is a practical way to mitigate this risk. By maintaining a cash cushion for immediate needs, you avoid being forced to sell long-term investments during a downturn.
Inflation is another persistent threat that erodes your purchasing power over a 20-30 year retirement. This is why we emphasize diversification across various asset classes. A portfolio with growth-oriented investments can help generate the returns needed to outpace inflation while managing overall risk.
More on our wealth management services
The Importance of Asset Consolidation and Regular Reviews
Over a career, you might accumulate several retirement accounts. Consolidating these assets, where appropriate, can greatly simplify your financial life. It provides a clearer picture of your overall portfolio, making it easier to rebalance, calculate RMDs, and manage withdrawals efficiently.
Your retirement plan isn’t something you create once and forget. We recommend annual reviews to ensure your strategy remains aligned with your life, market conditions, and tax laws. Changes in health, family, or spending goals can all warrant adjustments to your withdrawal approach.
For families in Charlottesville, Richmond, and across Virginia, a regular check-in with your advisor helps maintain peace of mind. It’s an opportunity to ask questions and make thoughtful adjustments before small issues become larger problems.
Learn about financial planning in Charlottesville, VA
The Role of a Fiduciary Advisor in Your Retirement Drawdown Strategy
Navigating the complexities of retirement income can feel overwhelming. This is where the guidance of a fiduciary advisor becomes invaluable. As fiduciaries, we are legally and ethically bound to act solely in your best interest.
We don’t earn commissions on products; our focus is on helping you build a plan that serves your long-term goals. We help you steer through the details of RMDs, tax implications, and market volatility. Perhaps most importantly, during periods of market uncertainty, our role includes providing calm, steady behavioral coaching. Having an experienced, objective perspective helps you stick to your long-term plan rather than making emotional decisions.
An advisor who knows your full financial picture can also help you see opportunities you might miss, such as strategic Roth conversions or tax-loss harvesting. These strategies require coordination and a deep understanding of tax law—areas where professional guidance adds real value.
Find a financial advisor in Charlottesville, VA
FAQs
How often should I review my retirement withdrawal strategy?
We recommend an annual review. Think of it as a yearly physical for your financial health. It’s also wise to revisit your plan after major life events, such as a health diagnosis, the loss of a spouse, or a significant shift in your goals. A well-designed retirement drawdown strategy is built to adapt.
What if the market drops soon after I retire?
This is a valid concern, known as sequence of returns risk. A thoughtful plan anticipates this. For instance, a bucket strategy keeps 1-3 years of living expenses in cash. This cushion means you aren’t forced to sell investments at a loss during a downturn, giving your long-term holdings time to recover.
Can I change my withdrawal strategy after I start?
Absolutely. Flexibility is a hallmark of a sound plan. Your needs will evolve, tax laws will change, and markets will shift. Your retirement drawdown strategies should support your life, not constrain it. Regular reviews help ensure your plan stays aligned with what matters most.
How do I decide when to start Social Security?
This is a personal decision with no single right answer. It depends on your health, family longevity, other income sources, and overall financial plan. Starting at 62 gives you income sooner but at a permanently reduced rate. Delaying until age 70 maximizes your monthly payment. For couples, the decision is more nuanced, as it also affects survivor benefits.
How do we coordinate withdrawals if my spouse and I have different retirement accounts?
It’s critical to think of your finances as a household. You might have a 401(k), an IRA, and Roth accounts between you. Coordinating withdrawals means looking at your combined income needs and pulling from the right accounts at the right time to minimize taxes and meet RMDs. This is one area where professional guidance can add significant value.
Moving Forward with a Clear and Confident Plan
You’ve spent years building your savings. Now, as you move into retirement, the question shifts from “How do I save enough?” to “How do I make this last?”
The good news is that retirement drawdown strategies don’t have to be overwhelming. With a clear, principled approach, you can create a plan that supports the life you’ve envisioned—one that balances your need for income today with confidence for the decades to come.
At Acadia Wealth Advisors, we work with families across Virginia—in Charlottesville, Richmond, Northern Virginia, and beyond—to bring clarity to retirement planning. Our goal is to help you understand your options, make informed decisions, and build a plan that adapts as your life and the markets change.
We know that confidence comes from having a thoughtful framework and a trusted partner who acts in your best interest. Your retirement plan should reflect your unique goals, your family’s needs, and your vision for the future.
Retirement is about the freedom to enjoy the life you’ve worked so hard to build. A well-designed drawdown plan makes that possible by giving you a clear path forward and the flexibility to adjust as life unfolds.
If you’re ready to move from uncertainty to clarity, we’d be honored to walk alongside you. Learn more about our retirement planning process.