

Why Multi-Generational Wealth Planning Matters Now
Multi-generational wealth planning strategies are designed to preserve and grow family assets across multiple generations while preparing heirs to manage that wealth responsibly. The most effective approaches combine clear governance structures, open communication, tax-efficient legal tools, and intentional education—all grounded in shared family values.
Key strategies for multi-generational wealth planning include:
- Establishing family governance through regular meetings, a family mission statement, and clear decision-making processes
- Implementing estate structures such as trusts, wills, and tax-efficient gifting strategies to protect assets and minimize tax liabilities
- Educating the next generation through age-appropriate financial literacy, mentorship, and hands-on experience with wealth management
- Planning for business succession with clear transition plans, identified successors, and appropriate legal structures
- Integrating philanthropy to reinforce family values and provide learning opportunities for younger members
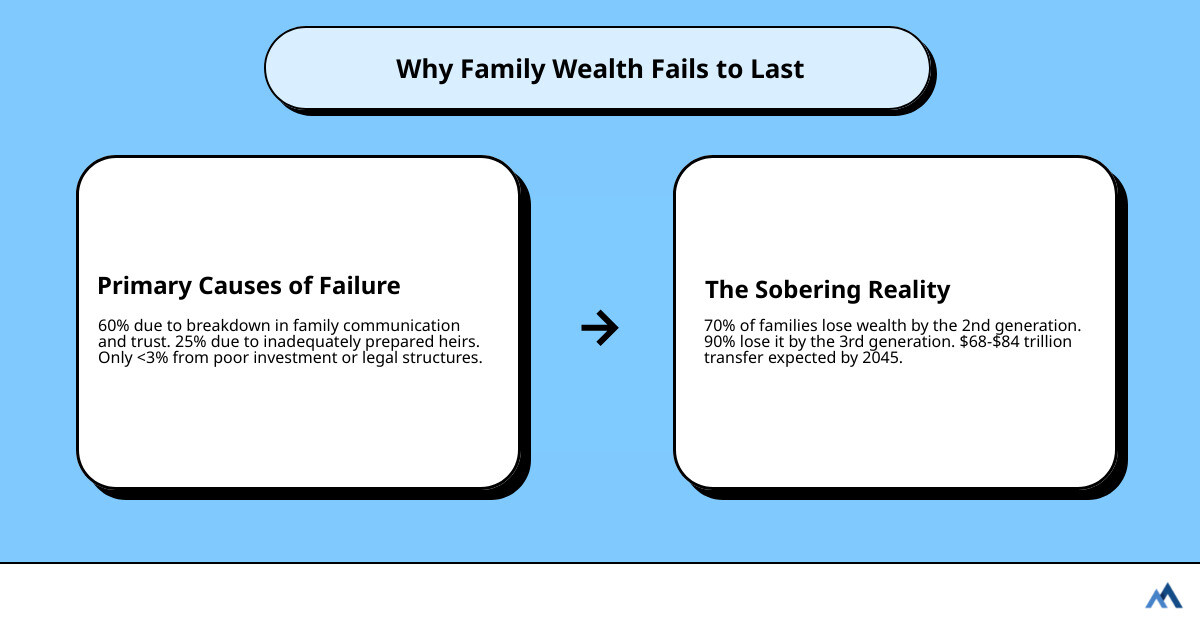
The data on wealth transfer is sobering. Roughly 70% of families lose their wealth by the second generation, and 90% by the third. Yet less than 3% of these failures stem from poor investment returns or inadequate legal structures. The primary causes are breakdowns in family communication and trust (60%), followed by inadequately prepared heirs (25%).
We’re entering a period of unusually large wealth transfers. Over the coming decades, baby boomers are expected to oversee one of the largest wealth transfers in history, passing significant assets to their spouses and descendants. This represents not just a transfer of assets, but a critical moment for families to define what wealth means beyond the balance sheet.
Successful multi-generational planning requires more than financial acumen. It demands clarity about family values, open dialogue about money and expectations, intentional preparation of the next generation, and systems that can adapt as both the family and economic landscape evolve. The families who sustain wealth do so by treating it as a shared responsibility rather than an individual entitlement.
I’m Frank Gristina, founder and portfolio manager at Acadia Wealth Advisors, where I’ve spent over 25 years helping families steer both planned transitions and unexpected events with a disciplined, data-informed approach. Throughout my career, I’ve seen how effective multi-generational wealth planning strategies require not just technical expertise, but a deep understanding of family dynamics and the patience to build systems that serve generations yet to come.
The Foundational Pillars: Governance and Communication
The technical aspects of wealth planning—the trusts, tax strategies, investment structures—matter considerably. But they’re not typically where things fall apart. When we look at families who’ve lost wealth across generations, 60% of the time it comes down to communication breakdowns and eroded trust. The numbers tell us something important: the conversation matters as much as the portfolio.
Family governance provides structure for those conversations. It’s not about creating bureaucracy or formal rules for their own sake. Rather, it’s about establishing clear expectations and a shared understanding of how decisions get made. When families define a family mission statement and articulate their shared values, they create a framework that guides both financial choices and philanthropic work.
Many families find that a family council—a regular forum where family members gather to discuss financial matters, make decisions, and address concerns—gives everyone a voice. These meetings create space for older generations to share their experience while younger family members contribute their perspectives. This isn’t about achieving perfect consensus on every decision. It’s about building a process that respects different viewpoints and resolves conflicts before they harden into lasting divisions.
The framework we help families build adapts as circumstances change. A governance structure that works when children are young will need to evolve as they become adults with their own families. The goal is clarity and mutual understanding across those transitions. For more on how we approach these foundational elements, you can review our work on Wealth Transfer and Legacy Planning.
Fostering Financial Transparency Across Generations
Parents often hesitate to discuss finances openly with their children. The concerns are understandable—will knowledge of future inheritance create dependency? Will it change their motivation? These are legitimate questions, but silence carries its own risks.
Research suggests that many U.S. adults received limited or no money lessons from their parents as children. That gap in preparation shows up later, often at precisely the wrong moment. Creating a safe space for financial conversations doesn’t mean revealing every detail at once. It means gradually involving younger generations in discussions that match their maturity level.
Financial transparency is about more than numbers. It’s about sharing the family’s financial philosophy, the choices that shaped current circumstances, and the responsibilities that come with wealth. When younger family members understand the thinking behind financial decisions, they develop their own capacity for sound judgment. The New York Times offers practical guidance on how to talk about money that many families find useful as they begin these conversations.
Managing expectations matters too. When heirs have realistic information about what they’ll inherit and when, they can plan their own lives more effectively. Uncertainty often causes more problems than difficult truths.
Integrating Family Values into Your Wealth Plan
Multi-generational wealth planning strategies gain strength when they’re grounded in clearly defined family values. These values function as a compass, informing investment choices, philanthropic work, and the broader purpose of the family’s wealth.
Some families prioritize education, structuring their wealth plan to fund learning opportunities across generations. Others focus on entrepreneurship, community impact, or environmental stewardship. There’s no single right answer, but there is value in being explicit about what matters most.
Documenting these values—through a family mission statement or what some call a “family constitution”—creates a reference point for future decisions. This isn’t a legally binding document. It’s a record of the family’s collective thinking about how wealth should serve its goals. It captures family history, articulates vision, and establishes principles for decision-making.
When families take time to define their values and connect them to their financial plan, wealth becomes more than assets on a balance sheet. It becomes a tool for achieving shared objectives that extend across generations. This alignment between values and resources is what transforms a technical wealth transfer into a lasting legacy.
Core Financial and Legal Structures for Multi-Generational Wealth Planning Strategies
The human elements—communication, values, governance—form the foundation of lasting wealth transfer. But they need to rest on something solid. That’s where the financial and legal structures come in. These are the practical tools that protect assets, minimize tax exposure, and ensure your intentions are carried out as planned. Our approach to Estate Planning focuses on building these structures to work in concert with your family’s specific circumstances and goals.
The Role of Wills and Trusts
A will is essential—it designates how your assets should be distributed and who will manage that process. But for families planning across multiple generations, trusts offer a level of control and protection that wills alone cannot provide.
The distinction between revocable and irrevocable trusts matters. A revocable trust gives you flexibility during your lifetime. You can modify terms, add or remove assets, or dissolve it entirely. It avoids probate, which can be time-consuming and public. An irrevocable trust requires you to give up direct control, but in exchange, it removes those assets from your taxable estate and provides stronger protection from creditors.
For multi-generational wealth planning strategies, certain trust structures are particularly useful. Generation-skipping trusts allow you to transfer wealth directly to grandchildren, potentially avoiding estate taxes in your children’s generation. Special needs trusts provide for family members with disabilities without affecting their eligibility for government benefits. Many families build in distribution standards—such as the HEMS standard (Health, Education, Maintenance, and Support)—to guide trustees in making distributions that support beneficiaries without creating dependency.
Appointing the right trustee is equally important. This person or institution will carry out your wishes, manage assets responsibly, and steer family dynamics. The structure should serve your family, not constrain it unnecessarily.
Navigating Key Tax Considerations
Tax planning isn’t about avoiding obligations—it’s about structuring transfers intelligently so more of what you’ve built reaches the people and causes you care about.
The federal estate tax exemption is a historically high figure ($13.61 million per individual for 2024). However, under current law, this exemption is scheduled to be reduced significantly in 2026. This creates a meaningful opportunity for families to make strategic gifts now. The IRS has confirmed through its ‘no-clawback’ rule that gifts made under the current higher exemption won’t be retroactively taxed if the limit decreases. You can review current exemption amounts for the latest details.
Beyond the lifetime exemption, the annual gift tax exclusion for 2024 is $18,000 per recipient. Over time, systematic gifting can move substantial wealth out of your estate without touching your lifetime exemption. Charitable giving offers another avenue—it reduces both taxable income and estate size while aligning your wealth with your values.
Tax-advantaged retirement accounts deserve attention as well. Traditional and Roth IRAs offer different tax benefits depending on your circumstances, and Health Savings Accounts (HSAs) provide a triple advantage: tax-deductible contributions, tax-deferred growth, and tax-free withdrawals for qualified medical expenses. The IRS guide on individual retirement arrangements offers comprehensive information on these vehicles.
The specifics matter here. Tax law changes regularly, and what works for one family may not suit another. But the principle remains consistent: thoughtful planning around these structures preserves more wealth for the generations ahead.
Advanced Multi-Generational Wealth Planning Strategies for Growth and Preservation
Foundational structures provide stability, but sustaining wealth across generations requires thoughtful approaches to growth, business transition, and asset diversification. Our work with Financial Planning for High Net Worth Individuals centers on these more nuanced aspects of multi-generational wealth planning strategies—ensuring that wealth compounds steadily while remaining accessible when needed.
Developing Effective Multi-Generational Wealth Planning Strategies for Business Succession
When a family business represents a significant portion of wealth, succession planning becomes central to the entire multi-generational strategy. This process typically unfolds over years, not months, and extends well beyond the mechanics of transferring ownership.
The data on business succession reveals an interesting pattern: roughly 75% of business owners experience seller’s remorse after a transaction. This often stems from inadequate transition planning or a lack of clarity about what comes next. Only about 4% of business owners have a formal plan for life after the sale, which speaks to how emotionally and practically complex these transitions can be.
Effective succession planning begins with identifying and mentoring potential successors, whether family members or key employees. A business that operates independently of its founder is both more valuable and more resilient. This means developing a strong management team and gradually transferring knowledge and decision-making authority over time.
Valuation and structure are equally important. Professional valuation provides a clear baseline, and ensuring that financials follow standard accounting practices makes any transition smoother. Families have several structural options: gifting shares to the next generation, arranging a sale to family members, or implementing an Employee Stock Ownership Plan (ESOP), which allows for a gradual transfer of ownership, often to employees who may also be family members. Transferring the business through trusts can offer both tax advantages and continued control over how the business is managed.
A comprehensive transition plan outlines the timeline, responsibilities, and legal framework for transferring both ownership and leadership. This includes buy-sell agreements, which establish terms for future transfers, and careful consideration of the emotional and financial realities of stepping back from a business you’ve built. We guide families through these layers, helping them shape a transition that honors their legacy while positioning the business for continued success.
Managing Alternative Investments and Liquidity
As portfolios grow, many families diversify into alternative investments—private equity, real estate, hedge funds—which can offer meaningful growth potential and reduce correlation with public markets. Among ultra-high-net-worth families, alternatives often represent 30% to 45% of total wealth. These assets introduce specific considerations within a multi-generational context.
Due diligence is essential before committing capital to any alternative investment, and ongoing tracking becomes critical due to their illiquid nature and often limited reporting transparency. Unlike publicly traded securities, alternatives don’t offer daily pricing or easy exits, which requires a different approach to portfolio management.
Liquidity planning takes on heightened importance when a significant portion of wealth is tied up in illiquid assets. These investments often come with capital calls—requests for additional funding—and generate tax distributions that require cash on hand. Forecasting liquidity needs 12 to 24 months ahead allows families to meet these obligations without disrupting their broader financial plan.
We typically recommend maintaining six to twelve months of living expenses in liquid instruments, with credit lines available for unexpected capital calls or opportunities. This cushion prevents the need to sell assets at inopportune times, which can significantly erode long-term wealth. Thoughtful liquidity management ensures that a family’s investment strategy remains resilient through market cycles and across generations.
Cultivating Stewardship in the Next Generation

The most sophisticated legal structures and investment strategies will not sustain wealth if the next generation is unprepared to manage it. This is not a theoretical concern. Twenty-five percent of generational wealth transfer failures occur because heirs lack adequate preparation. Our experience shows that multi-generational wealth planning strategies must include intentional education and mentorship, treating the development of capable stewards as seriously as asset allocation or tax planning.
Financial education needs to begin early, but not with lectures about compound interest. Young children can grasp basic concepts through experience—earning an allowance, making choices about saving versus spending, setting aside money for giving. These foundational habits matter more than technical knowledge at this stage. As they mature, the conversations naturally evolve to include budgeting, understanding investment principles, and the family’s approach to wealth.
We have found that hands-on experience accelerates learning in ways that classroom instruction cannot. This might involve a young adult managing a small investment allocation, participating in family council discussions, or shadowing older family members through financial decisions. The goal is not perfection but engagement—developing comfort with financial concepts and building confidence in their judgment. Mentorship from trusted advisors or experienced family members provides a safe environment to ask questions, make small mistakes, and understand that wealth management is a skill developed over time.
For families seeking structured resources, Investopedia offers a helpful list of 7 finance books for children that can complement these experiential lessons. The broader research on the importance of financial education confirms what we observe in practice: early, consistent exposure to financial concepts builds competence and reduces anxiety around money.
Educating Heirs for Responsible Wealth Management
The curriculum for heir education should mirror the complexity of the family’s wealth. Families with significant business interests need to prepare successors differently than those with primarily liquid portfolios. This customization matters because generic financial education rarely addresses the specific challenges your heirs will face.
We encourage families to create opportunities for younger members to observe decision-making processes before they are asked to lead them. Attending investment committee meetings, reviewing portfolio performance reports, or participating in discussions about charitable giving all provide context that cannot be taught from textbooks. These experiences also reveal individual aptitudes and interests, helping the family understand which members might take on fiduciary roles and which might contribute in other capacities.
The objective is not to produce professional investors in every family member, but to cultivate a stewardship mindset. Heirs should understand that wealth carries responsibilities, that it can be a tool for meaningful impact, and that maintaining it requires discipline and informed judgment. This perspective helps prevent the entitlement or anxiety that can emerge when wealth transfer happens without adequate preparation.
Integrating Philanthropic Goals into Your Multi-Generational Wealth Planning Strategies
Philanthropy serves multiple purposes in a multi-generational wealth planning strategy. It reinforces family values, provides practical learning experiences for younger generations, and creates shared purpose across age groups. Families who engage in structured giving often report stronger cohesion and more productive conversations about wealth.
Defining a clear philanthropic mission provides direction. What issues matter to your family? What kind of impact do you hope to achieve? How will your giving reflect the values you want to pass forward? These questions help transform philanthropy from occasional donations into a meaningful component of your family’s identity.
The structural options for organized giving typically include Donor-Advised Funds (DAFs) and private foundations. DAFs offer simplicity, immediate tax deductions, and low administrative burden, making them accessible for families beginning their philanthropic journey. Private foundations provide greater control and transparency, along with a formal structure for family involvement in grant-making decisions. Both vehicles can be effective; the choice depends on your family’s priorities and desired level of engagement.
Involving younger family members in philanthropic decisions creates a safe environment to develop financial judgment. Researching organizations, assessing their effectiveness, and making grant recommendations all build skills in due diligence and critical thinking. These lessons transfer directly to other aspects of wealth management. Moreover, philanthropy often opens conversations about values and purpose that might feel awkward in purely financial contexts.
Measuring impact adds another dimension to the learning process. Younger generations often want to see tangible results from their giving, and this accountability mindset serves them well as future stewards of family wealth. Shared family projects—whether funding a scholarship program, supporting a local initiative, or addressing a cause that resonates across generations—create memories and meaning that outlast any individual transaction.
An inheritance left directly to a family member with a disability can disqualify them from SSI or Medicaid, which is why financial planning for families with a special needs child usually routes those assets through a special needs trust.
The families we work with who integrate philanthropy into their planning consistently report that it strengthens relationships and provides a framework for discussing wealth that feels purposeful rather than burdensome. It transforms inheritance from a passive receipt of assets into an active commitment to stewardship.
Frequently Asked Questions about Multi-Generational Wealth Planning
How is multi-generational planning different from standard estate planning?
Standard estate planning typically addresses the transfer of assets at death, often with a focus on tax efficiency and basic legal documentation. Multi-generational wealth planning strategies operate on a broader timeline and encompass more than the mechanics of asset transfer.
The distinction lies in scope and continuity. Multi-generational planning is an ongoing process that weaves together family governance structures, the articulation of shared values, the intentional preparation of heirs, and systems designed to adapt as circumstances change. It considers how a family will make decisions together, how younger generations will develop the capacity to manage wealth responsibly, and how the family’s resources will serve its purpose across decades.
Where estate planning often concludes with the execution of documents, multi-generational planning begins there. It addresses questions about how the family will communicate about money, how conflicts will be resolved, and how each generation will understand its role as a steward rather than simply an inheritor.
What is the most common reason multi-generational wealth transfers fail?
The data here is instructive. Poor investment performance or inadequate legal structures account for only about 3% of failed wealth transfers. The primary cause, representing 60% of failures, is a breakdown in family communication and trust. The second most common cause, at 25%, is inadequately prepared heirs.
This tells us that the technical aspects of wealth preservation—while important—are not where most families struggle. The challenges are human. They involve whether family members can talk openly about expectations, whether younger generations have been given the tools and experience to manage responsibility, and whether the family has built systems that foster understanding rather than resentment or confusion.
Addressing these elements requires intention. It means creating opportunities for dialogue, establishing clear governance processes, and investing time in the education and development of the next generation. These are not one-time conversations but ongoing commitments that evolve as the family grows.
At what age should financial education for the next generation begin?
Financial education can begin early, often in childhood, with concepts appropriate to a young person’s understanding. Simple ideas like saving a portion of an allowance, understanding that purchases involve trade-offs, or participating in family decisions about charitable giving can lay a foundation.
As children mature, the complexity of these conversations naturally increases. Adolescents might learn about budgeting or the basics of how investments grow over time. Young adults can engage with more sophisticated topics—understanding the family’s investment philosophy, participating in family council meetings, or managing a small allocation under guidance.
The key is consistency and relevance. Financial education should not feel like a lecture but rather an ongoing dialogue that meets each person where they are. The goal is to build competence and confidence gradually, so that by the time significant responsibility arrives, it feels like a natural progression rather than an abrupt shift. Every family’s timeline will differ based on individual readiness and circumstances, but starting early and maintaining engagement throughout development is a sound approach.
Partnering for a Lasting Legacy
Developing and sustaining effective multi-generational wealth planning strategies is an ongoing process that requires both technical expertise and an understanding of how families evolve over time. At Acadia Wealth Advisors, we recognize that successful planning integrates financial structures with the human elements—communication, values, and preparation—that research shows are most critical to preserving wealth across generations.
Our approach is rooted in data-driven guidance, but we understand that numbers alone don’t capture what families are working toward. Your legacy encompasses the values you’ve defined, the opportunities you create, and the stewardship you instill in those who follow. We work with families in Virginia, Georgia, Texas, and Tennessee to build strategies that are both technically sound and personally meaningful.
What sets our work apart is the combination of disciplined portfolio management and a long-term perspective on family dynamics. We help families establish the governance structures and communication frameworks that make wealth transfer more likely to succeed. We implement the legal and tax-efficient tools that protect assets. And we support the educational and philanthropic initiatives that prepare the next generation to carry forward what you’ve built.
Plans only work if they keep pace with the family and the rules around them. We maintain long-term partnerships with our clients, revisiting strategies regularly to ensure they remain aligned with your objectives. This ongoing relationship means we’re positioned to help you steer both anticipated transitions and unexpected developments.
If you’re considering how to structure your family’s wealth for the long term, we invite you to explore how our experience and approach might serve your goals. Learn more about our approach to Wealth Transfer and Legacy Planning.