

Why the Investing Bucket Strategy Matters for Your Retirement
The investing bucket strategy is a retirement income approach that divides your portfolio into three separate “buckets” based on when you’ll need the money:
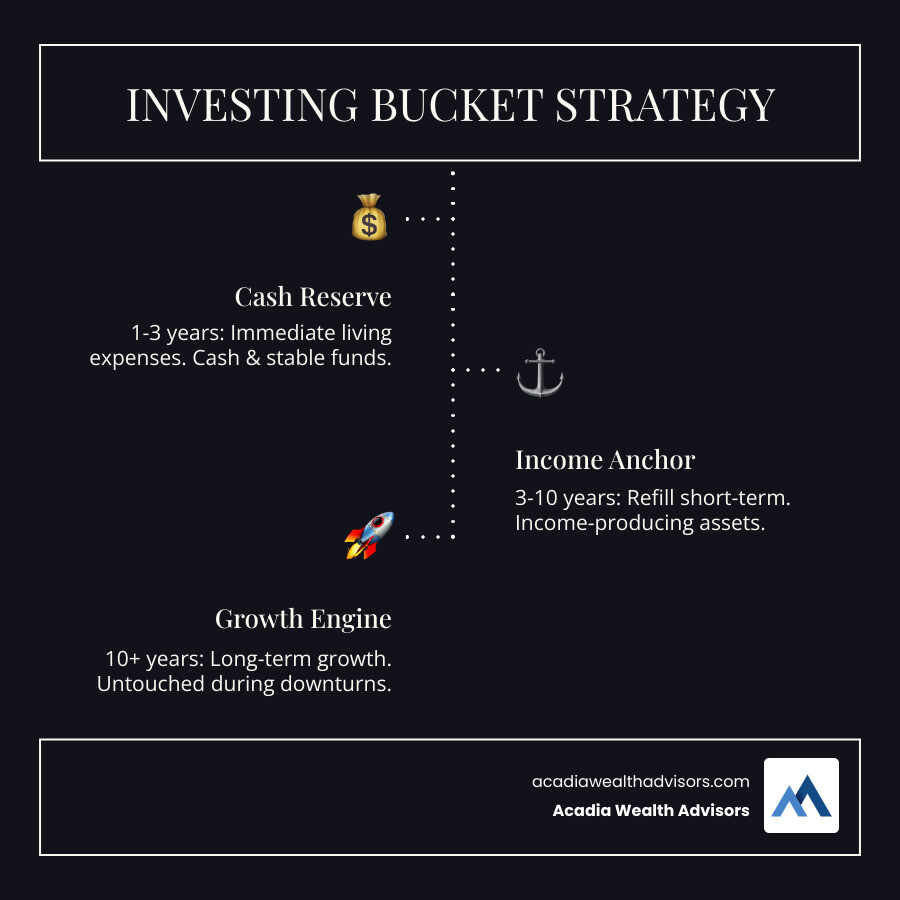
- Short-term bucket (1-3 years) – Cash and stable investments for immediate living expenses
- Medium-term bucket (3-10 years) – Conservative income-producing assets to refill your cash
- Long-term bucket (10+ years) – Growth investments that remain untouched during market downturns
This structure helps protect you from being forced to sell stocks during a bear market while ensuring you have reliable access to income throughout retirement.
A common question we hear from families in Charlottesville is simple but profound: How do I turn a lifetime of savings into a reliable paycheck? The concern is real. Market volatility doesn’t stop when you retire. In fact, the sequence of returns you experience in your first few years of retirement can have an outsized impact on whether your money lasts 20 years or 40.
The investing bucket strategy offers a practical solution. Rather than holding everything in one portfolio and hoping for the best, you organize your assets based on when you’ll need them. This isn’t a product to buy or a complex financial instrument. It’s a framework – a way of thinking about your money that aligns your investments with your timeline.
For professionals and executives in Virginia who have spent decades building wealth, this approach provides something invaluable: clarity. You know where your next year’s income is coming from. You’re not checking stock prices every morning wondering if you can afford to pay your bills. Your growth assets have the time they need to work, and your near-term expenses are secure.
I’m Frank Gristina, and with over 25 years of experience managing portfolios, I’ve seen how the investing bucket strategy helps families move from accumulation to distribution with confidence. At Acadia Wealth Advisors, we use this principle-driven approach to help clients in Richmond, Northern Virginia, and Albemarle County structure their retirement income so it feels grounded and sustainable.
Who This Is For
This guide is for you if you are nearing or in retirement, feeling unsure how to protect your nest egg from market swings while still paying your bills, or wondering how to structure your investments for both income and growth. Specifically, it’s designed for:
- Pre-retirees who want to build a clear roadmap for transitioning from saving to spending.
- Retirees seeking a structured, predictable way to draw income from their investments.
- Individuals concerned about market volatility and how it might impact their ability to cover living expenses.
If You’re Wondering…
You might be struggling with questions like these:
- How can I create a predictable retirement paycheck that lasts as long as I do?
- How do I avoid being forced to sell stocks at a loss during a market downturn just to cover my daily needs?
- Is there a way to organize my different retirement accounts (401(k), IRA, Roth) more effectively?
- How can I feel more confident about my spending decisions throughout my retirement years?
How This Guide Brings Clarity
This guide explains the investing bucket strategy, a time-tested method for organizing your retirement assets. It’s a way of thinking that aligns your money with your timeline, creating a buffer against market volatility. This gives your long-term investments time to grow while providing for near-term expenses with confidence. We will walk through what the strategy is, how to set it up, and how to maintain it.
What Is the Investing Bucket Strategy?
The investing bucket strategy is built on a straightforward idea: organize your portfolio into separate sections based on when you’ll actually need the money. Think of it as creating different accounts for different purposes, each matched to a specific timeline in your life.
Instead of holding all your money in one big portfolio and hoping the market cooperates when you need to pay bills, you deliberately separate your funds by purpose. Your grocery money for next year sits in a different place than your travel fund for five years from now, which sits in a different place than the wealth you want to preserve for your grandchildren.
This structure protects you from sequence-of-return risk. This is the danger that a market downturn in your first few years of retirement could derail your entire plan. When you withdraw money from a portfolio that has just dropped in value, you compound the damage, making it harder for your money to last.
The investing bucket strategy addresses this head-on. When stocks are down, you’re not forced to sell them. You simply draw from the cash and stable assets you’ve set aside, giving your growth investments the time they need to recover.
The Goal: Aligning Your Timeline with Your Investments
The strategy divides your money into three categories. Bucket 1 holds cash for your immediate needs (1-3 years). Bucket 2 is for your intermediate timeline (3-10 years). Bucket 3 is for long-term growth, with funds you won’t touch for at least a decade.
This separation allows you to take on the right amount of risk for each portion of your portfolio. Your short-term money stays safe and accessible. Your long-term money can ride out volatility because it has time to grow. And your medium-term bucket acts as a bridge between the two.
The real benefit? You’re never forced to sell growth assets at the wrong time just to cover living expenses. When the market drops, your cash bucket is already full. When stocks recover and climb, you can sell some at a profit to refill your near-term reserves. It’s a disciplined approach that helps you “sell high” rather than panic-selling during downturns.
Think of it like water flowing between reservoirs. Your first bucket is small but always full and ready. The second is larger, designed to steadily refill the first. The third is the largest—a deep reserve where your wealth can grow, only tapped when conditions are favorable.
Why This Approach Resonates with Retirees

For professionals and families in Richmond and Northern Virginia, the investing bucket strategy offers something that’s hard to put a price on: peace of mind. It shifts your focus from trying to predict market movements to simply managing a clear system.
Many investors make emotional decisions, buying high out of excitement and selling low out of fear, which can harm long-term returns. The bucket approach helps you avoid this trap by creating a clear system, so your long-term investments can remain untouched during volatile periods.
For families in Charlottesville preparing for retirement, knowing that your grocery bills and healthcare costs are covered – regardless of what the stock market does tomorrow – creates a foundation of confidence. You’re not checking your portfolio every morning wondering if you can afford your plans. You have a logical structure, and that structure gives you the freedom to focus on what retirement is really about: living well.
We’ve seen how this clarity transforms the retirement experience for clients across Virginia. It’s not about guaranteeing returns or eliminating all risk. It’s about creating a framework that feels grounded and sustainable, so you can move forward with a steady hand.
Structuring Your Buckets: Short, Medium, and Long-Term Planning
The most common approach uses three buckets, each with a distinct purpose and investment profile. The key is to match the assets in each bucket to its specific time horizon. Think of it as organizing your financial life into three distinct drawers – one for what you need now, one for what’s coming soon, and one for the distant future.
This alignment between your timeline and your investments isn’t just good planning. It’s what allows you to sleep well at night when the market gets choppy.
Bucket 1: The Cash Reserve (1-3 Years)
This bucket is for your near-term living expenses. Its primary goal is principal stability, not growth. It should hold 1 to 3 years of the expenses your portfolio needs to cover, after accounting for Social Security, pensions, or other income.
This cash buffer is your financial peace of mind. If the market takes a dip – and it will – you simply draw from this bucket. Your other investments get the time they need to recover without being forced to sell them at a loss. It’s like having an umbrella before the rain starts.
Typical assets for your cash reserve include cash, high-yield savings accounts, money market funds, and short-term Certificates of Deposit (CDs). The goal of this bucket is not high returns, but safety and immediate accessibility to pay your bills.
Bucket 2: The Income Anchor (3-10 Years)
This bucket acts as a bridge between your short-term cash and your long-term growth assets. It’s designed to generate income and provide some growth while maintaining relative stability. This is also the bucket you use to refill Bucket 1 when it starts to run low.
Think of this as your middle ground. The assets are less volatile than stocks but offer higher returns than cash. This balance is intentional: you can take on some risk for growth, but not so much that a market downturn threatens funds you’ll need in the next few years.
Your income anchor typically holds high-quality bonds, bond funds, conservative balanced funds, and some dividend-paying stocks. These investments provide a steady stream of income and moderate growth, helping to replenish your cash reserve without exposing your long-term assets to unnecessary risk. For many families in Richmond and Charlottesville, this bucket becomes the workhorse of their retirement income plan.
Bucket 3: The Growth Engine (10+ Years)
This is your long-term capital, invested for growth to ensure your portfolio lasts throughout a long retirement. This bucket will experience the most volatility – sometimes significantly – but it also has the highest potential for long-term returns. It’s designed to be left untouched for at least a decade, giving your investments ample time to ride out market fluctuations and benefit from compounding.
Here’s where patience pays off. When the market drops 20% and everyone is panicking, you’re not selling these assets to cover your grocery bills. You’re drawing from Buckets 1 and 2 instead, letting this bucket do what it’s meant to do: grow over time.
Your growth engine typically includes diversified stock funds, individual stocks with growth potential, index funds, and other growth-oriented assets. This is where your wealth continues to grow for the later stages of your retirement, supporting your lifestyle decades down the road. To learn more about how we help manage these types of investments, you can explore our wealth management services.
The beauty of the investing bucket strategy is that each bucket has a job. When they work together, you get both stability and growth – income for today and wealth for tomorrow.
Implementing Your Investing Bucket Strategy
Setting up your buckets is a thoughtful process that begins with understanding your own financial picture. It’s less about complex formulas and more about practical planning. The goal is to create a system that works for you, providing both security and the potential for growth.
The truth is, most people overthink this part. You don’t need a doctorate in finance to get started. You need clarity about what you spend, what you have, and when you’ll need it. The rest is just careful organization.
Have questions? We’re here to help you find clarity and move forward with confidence. Schedule a calm, pressure-free conversation with Acadia Wealth Advisors.
A Simple Checklist for Getting Started
Here’s how we walk families through the investing bucket strategy setup at Acadia Wealth Advisors.
First, estimate your expenses. Start by calculating your annual living expenses in retirement. Be realistic – include everything from utilities to travel to healthcare. Then subtract any reliable income sources you expect, such as Social Security or a pension. The remaining amount is what your investment portfolio needs to provide each year. Using an expense tracking app can be helpful here, and remember to factor in inflation over time. If you expect to spend $80,000 a year and receive $40,000 from Social Security, your portfolio needs to cover the $40,000 gap.
Second, size your buckets. Decide how many years of expenses you want to hold in Bucket 1 (the cash reserve) and Bucket 2 (the income anchor). A common approach for Bucket 1 is 1-3 years of expenses, and for Bucket 2, 5-8 years of expenses. Using our example above, if you need $40,000 annually from your portfolio and want two years in Bucket 1, you’d set aside $80,000 in cash. For Bucket 2, eight years would mean $320,000 in conservative income-producing assets. The remainder of your portfolio goes into Bucket 3, your growth engine.
Third, fund the buckets. Allocate your existing assets into the appropriate buckets based on their risk profile and your timeline. This might involve moving funds between accounts or even selling some assets and buying others to fit the bucket’s purpose. If you currently have everything in a mix of stocks and bonds, you’ll be intentionally reorganizing – perhaps liquidating some positions to build your cash reserve, shifting bond funds to Bucket 2, and concentrating your equity holdings in Bucket 3.
Finally, consider pre-retirement goals. The beauty of this logic is its flexibility. You can use this same bucket approach before retirement to save for other significant financial goals, like a house down payment in five years or college tuition in ten. You’d simply create a “medium-term bucket” specifically for that goal, balancing safety and growth for its particular time horizon.
Customizing Your Investing Bucket Strategy

The bucket structure is a framework, not a rigid rule. Your personal risk tolerance, your desire to leave an inheritance, your life expectancy, and your overall financial situation will influence your allocations.
For instance, a more risk-averse individual might keep more years of expenses in Bucket 1 and Bucket 2. We’ve worked with families in Richmond who simply sleep better knowing they have four years of cash set aside rather than two. That peace of mind is worth the slightly lower long-term returns on that portion of their portfolio.
Conversely, someone with a long life expectancy and a desire for aggressive growth might allocate more to Bucket 3. The number of centenarians in the U.S. population continues to grow, meaning longer retirements. If you’re 65 today and in good health, planning for a 30-year retirement isn’t pessimistic – it’s prudent.
Some families want to leave a substantial inheritance to their children or grandchildren. Others plan to spend their last dollar on their last day. These different goals lead to different bucket allocations, even for people with similar net worth.
A trusted Financial Advisor in Charlottesville, VA can help you tailor this strategy to your specific needs, ensuring it aligns with your unique circumstances and goals. We understand that every family in Virginia has a different financial story, and we’re here to help you write your next chapter with confidence.
Maintaining Your Buckets: Rebalancing, Taxes, and Managing Risk
The investing bucket strategy is not a “set it and forget it” plan. It requires periodic, disciplined maintenance to keep it working effectively. Think of it like tending a garden – you planted thoughtfully, and now you need to water, prune, and occasionally move things around to keep everything thriving.
The goal is straightforward: systematically refill your cash bucket so you always have funds available for your living expenses, while allowing your growth assets the time and space they need to flourish.
How to Refill Your Buckets
The primary task is to replenish Bucket 1 as you spend it down. This is where the strategy really shows its elegance.
During normal market conditions, you use the income and dividends generated from Buckets 2 and 3 to top off your cash reserve. Your bonds throw off interest. Your dividend-paying stocks send you quarterly checks. These natural cash flows move into Bucket 1 without you having to sell anything.
But what about years when the market does well? This is when the strategy gets even more powerful. During years of strong market performance, you can “trim” appreciated assets from Bucket 3 – your growth engine – and move the proceeds to Bucket 2 or directly to Bucket 1. This disciplined rebalancing helps you “sell high” from your growth assets. You’re taking profits when they’re there to be taken.
And crucially, this protects you from being forced to sell assets in a down market. If stocks are down 20%, you simply continue drawing from Buckets 1 and 2, letting Bucket 3 recover without touching it. This patience is what protects you from sequence-of-return risk.
Think of it as a flow: when Bucket 1 gets low, you draw from Bucket 2. When market conditions are favorable, you can replenish Bucket 2 with gains from Bucket 3. This ensures a steady flow of funds without touching your long-term investments when they are down.
The Role of Taxes in Your Investing Bucket Strategy

Tax efficiency is a key consideration, especially for high net worth individuals in Virginia. The type of account where you hold each bucket matters significantly – sometimes more than the investments themselves.
Here’s a common approach that can make sense: hold your cash (Bucket 1) in a taxable account for easy access. Place your bonds and income-generating assets (Bucket 2) in a tax-deferred IRA, where that interest income won’t create an annual tax bill. Then put your growth stocks (Bucket 3) in a Roth IRA to maximize tax-free growth in retirement.
You also need to understand Required Minimum Distributions (RMDs) from traditional IRAs and 401(k)s. These mandatory withdrawals start at age 73 (as of 2023), and they can throw a wrench into your bucket strategy if you haven’t planned for them. By strategically placing assets and planning your withdrawals, you can minimize your tax burden and ensure your money works harder for you.
This is a complex area where personalized advice can make a substantial difference. What works for a family in Richmond might look different from what makes sense for a professional in Northern Virginia, depending on their income sources, tax bracket, and estate planning goals.
A Balanced View: Pros, Cons, and Alternatives
Like any strategy, the bucket approach has benefits and drawbacks. We believe in being honest about both.
The main benefits are both psychological and practical. It provides a clear plan that reduces anxiety during market downturns. By ensuring you have cash reserves, it mitigates sequence-of-return risk and encourages a disciplined approach to withdrawals. The strategy is also flexible and can be customized to your individual needs, risk tolerance, and timeline.
The drawbacks are manageable. The strategy can be more involved to manage than a simple withdrawal approach. Holding a large cash reserve may also lead to lower overall returns and a loss of purchasing power due to inflation. However, for many, the peace of mind it offers outweighs these potential trade-offs.
There are alternatives to the bucket approach. Alternatives exist, like the 4% rule, which suggests withdrawing 4% of your portfolio in your first year of retirement and adjusting for inflation annually. Another is a systematic withdrawal plan, where you withdraw a set fraction of your portfolio each year based on your life expectancy.
The investing bucket strategy can also be used in conjunction with these methods, providing an organizational layer that improves their effectiveness and provides greater peace of mind. For many families in Charlottesville and across Virginia, it’s not about choosing one approach over another – it’s about finding the framework that helps you sleep well at night.
Ready to talk through your financial goals? Schedule a calm, pressure-free conversation with Acadia Wealth Advisors.
FAQs: Your Questions Answered
How many buckets should I have?
While three buckets is the most common structure, the system is flexible. Some people prefer a simpler two-bucket system (one for cash, one for everything else), while others may want four or more to align with specific goals. The right number depends on what provides you with the most clarity and confidence in managing your finances.
What happens if the stock market has a bad year?
This is exactly where the bucket strategy shows its strength. If your growth assets in Bucket 3 are down, you are not forced to sell them at a loss. You would simply continue to draw from your secure cash in Bucket 1 and use your more stable bond holdings in Bucket 2 to replenish it, giving your stocks valuable time to recover without crystallizing losses.
Is the bucket strategy only for retirement?
Not at all. The underlying principle of matching your timeline to your investments is useful at any stage of life. You can use a bucket approach to save for a house down payment in five years, college tuition in ten years, or any other major financial goal. It’s a versatile framework for organizing any long-term savings plan.
How often should I rebalance my buckets?
We typically recommend reviewing your buckets annually or when major life events occur, such as a significant market shift or a change in your spending needs. This allows you to maintain your strategy with discipline, rather than reacting to short-term market noise. The goal is to have a consistent process for refilling your cash bucket and keeping your allocations aligned.
Does this replace the need for a diversified portfolio?
Not at all. The bucket strategy is a way to structure your withdrawals and manage risk across your portfolio. Within Buckets 2 and 3, it is still essential to hold a well-diversified mix of assets appropriate for those time horizons. Diversification remains a cornerstone of prudent investment planning.
Conclusion: A Framework for Confidence
The investing bucket strategy is a powerful tool for navigating the transition from accumulating wealth to generating income in retirement. By organizing your assets with your spending timeline in mind, you create a durable framework that can help you weather market volatility with a steady hand. It is a practical, principle-driven approach that fosters clarity and confidence, allowing you to enjoy your retirement years without constant financial worry.
At Acadia Wealth Advisors, we believe that a sound Retirement Planning strategy is the foundation for a fulfilling life after work. Our approach is always calm, measured, and grounded in real expertise. We aim to provide clear, actionable guidance that empowers you to make good decisions for your long-term stability. This strategy isn’t about predicting the market; it’s about preparing for it, so you can live confidently in retirement, whether you’re in Charlottesville, Richmond, or anywhere across Virginia.