

Why Business Owners Face Unique Wealth Management Challenges
How to do wealth management for business owners starts with recognizing that your financial life works differently from that of a traditional employee. Much of your wealth may be tied up in a single, illiquid asset, your business, which means your personal financial security often rises and falls with the company. That concentration creates unique planning needs and requires a clearer separation between personal and business finances.
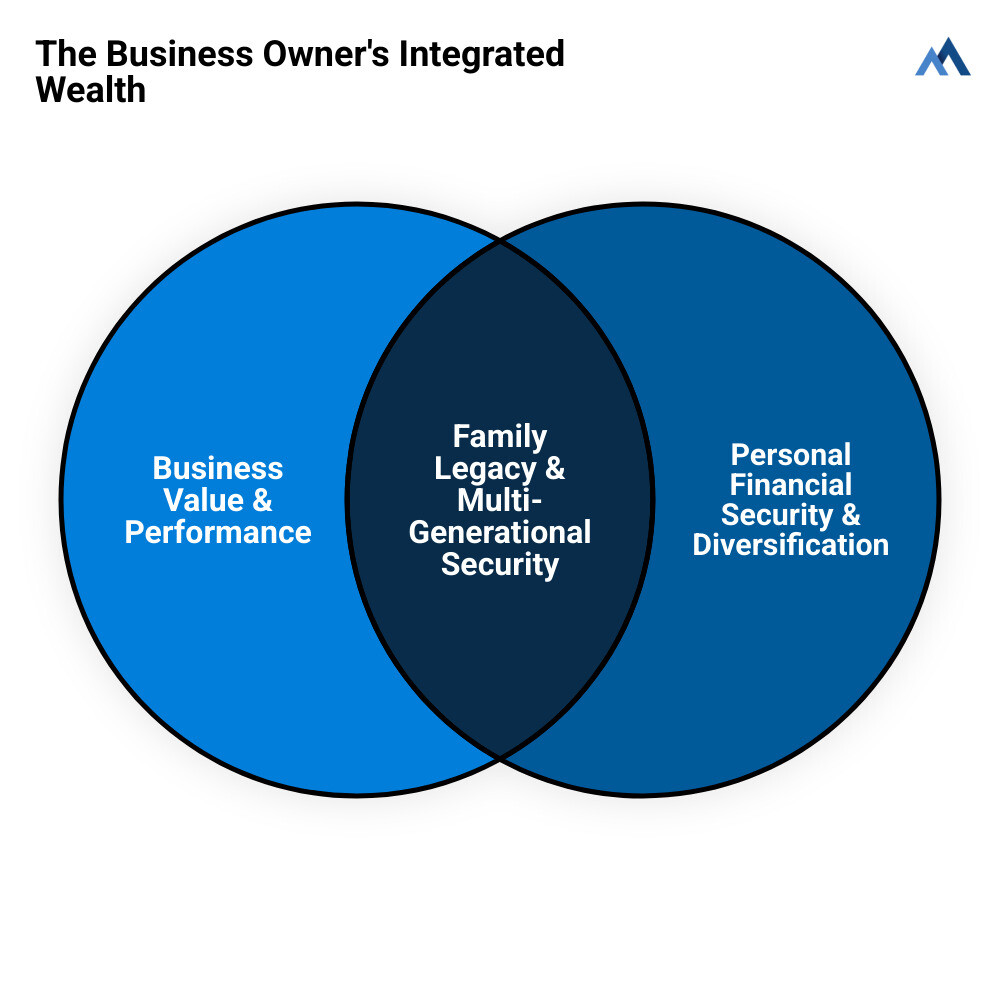
Effective wealth management for business owners requires a coordinated approach that connects both the business and personal sides of your finances:
- Separate business and personal finances through proper legal structures (LLC, S-corp) and dedicated accounts.
- Diversify beyond your business by systematically investing in assets unrelated to your company.
- Plan for retirement proactively using entrepreneur-specific vehicles like SEP IRAs or Solo 401(k)s.
- Develop a clear exit strategy, whether through sale, family succession, or a gradual transition.
- Implement tax optimization strategies that coordinate business and personal wealth planning.
- Protect assets with appropriate insurance (key person, disability, umbrella) and estate planning.
- Manage liquidity by balancing business reinvestment with personal wealth accumulation.
Many entrepreneurs find it difficult to turn years of effort into long-term financial security. Retirement savings often lag because most available capital is reinvested into the business, and a meaningful percentage of small businesses listed for sale never complete a transaction. That gap between business value and personal liquidity is one of the core planning challenges owners face.
The core challenge is that most of your net worth is tied up in your business, making it difficult to access cash, diversify risk, or plan for life after ownership. You need a strategy that addresses both your business assets and personal financial goals simultaneously.
As Frank Gristina, I’ve spent over 25 years helping business owners and their families steer the transition from building a business to creating lasting, multi-generational wealth. This guide outlines the essential strategies to help you protect what you’ve built and secure your financial future.
Foundational Strategies: Building a Resilient Financial Structure
A key part of how to do wealth management for business owners is maintaining a clear line between your business finances and your personal finances. Using business accounts for personal expenses or personally guaranteeing business debt without understanding the risks can create issues later and limit your financial flexibility.
Choosing the right business structure, such as an LLC or S-corporation, creates a legal barrier between business liabilities and your personal assets. This can be the difference between a business setback and a personal catastrophe. Maintaining separate accounts and financial discipline is equally critical.
A harder challenge is balancing reinvestment in the business with building your own wealth. It’s natural to reinvest profits for growth, but concentrating all your wealth in your company creates significant risk. Many entrepreneurs have insufficient retirement savings, not due to carelessness, but because the business always seems to need the capital more urgently than their future does.
Assembling Your Professional Team
As your company grows, the financial decisions surrounding it become more complex. It’s unrealistic to serve as your own tax strategist, estate attorney, and wealth manager, especially as the stakes increase.
A coordinated team of credentialed advisors is essential infrastructure. You need a tax advisor who understands business structures, an estate attorney to protect your legacy, and a wealth manager who sees how all the pieces fit together. When these professionals work in silos, you get conflicting advice and missed opportunities. When they work as a team, you get a cohesive strategy.
The wealth manager acts as the quarterback, coordinating with your other advisors to ensure your business decisions and personal wealth plan are aligned. Look for an advisor with specific experience working with business owners, who understands illiquid assets, concentrated positions, and exit planning. Credentials like CFP®, CFA®, or CPWA® signal a high level of training and ethical standards. You want someone who treats your company as the complex asset it is, not just a number on a balance sheet.
Balancing Business Growth with Personal Retirement Goals
It’s natural to reinvest heavily in a company that appears to offer strong returns. The challenge is that equity in a private business is often illiquid, and market conditions can change. Building personal savings outside the business gives you options later and helps ensure that your retirement plan doesn’t rely solely on the future sale of the company.
The discipline of “paying yourself first” is about building a financial life that doesn’t depend entirely on your company. Setting up and consistently contributing to a SEP IRA or Solo 401(k) creates a pool of wealth that is diversified, liquid, and protected, while also offering significant tax advantages.
This practice forces you to maintain balance and acknowledge that your business, however promising, is not your entire financial plan. This mindset shift—from “everything for the business” to “the business serves my life”—is often what separates owners who successfully transition to their next chapter from those who remain trapped in their companies.
How to Do Wealth Management for Business Owners Across the Business Lifecycle
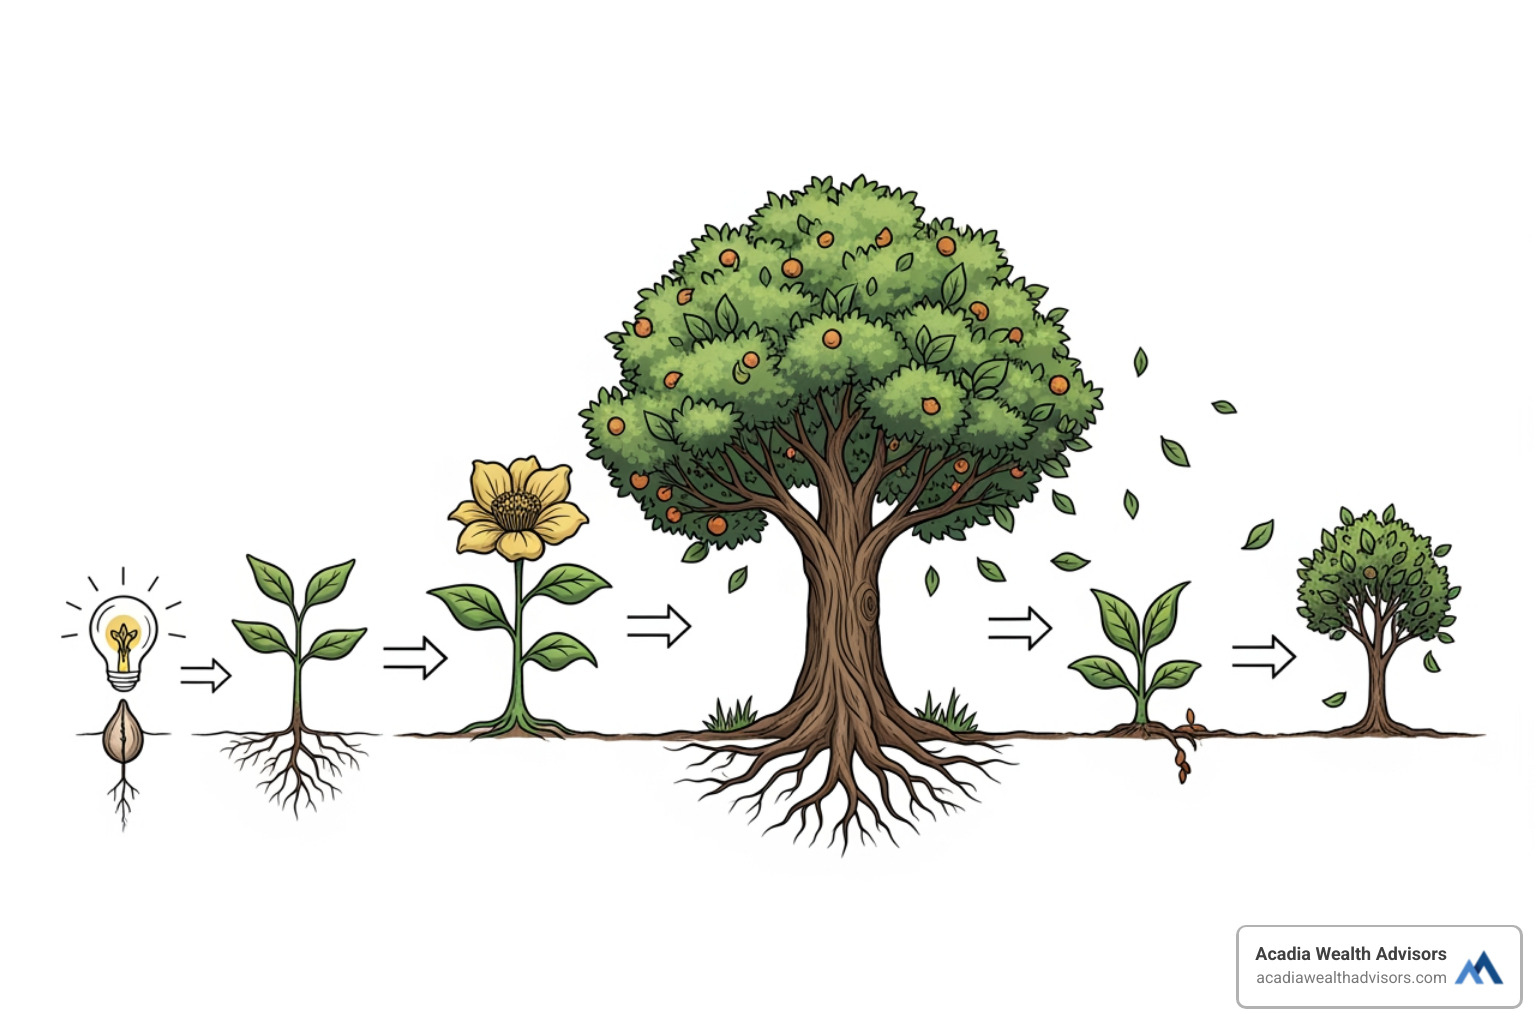
Your wealth management strategy must evolve with your business. The priorities of a startup founder are different from those of an owner preparing to sell a mature company. How to do wealth management for business owners is an ongoing process that adapts as your company moves from startup through growth, maturity, and eventual exit.
The Startup and Growth Stages: Fueling Growth While Managing Risk
In the early years, your business demands nearly all your time and capital. Even in these lean years, foundational decisions have lasting consequences.
During the startup phase, capital preservation matters as much as growth. Choosing the right business entity, often an LLC or S-corporation, helps establish a legal separation between business liabilities and personal assets, reducing the chance that a business setback affects your personal finances.
Managing debt thoughtfully is also critical. We help business owners distinguish between productive debt that fuels growth and risky leverage that creates personal financial exposure.
Even when most of your wealth is illiquid, initial diversification is important. This might mean setting up a SEP IRA and contributing what you can or maintaining a modest emergency fund outside the business. These small steps build a foundation for future financial stability. Liquidity management in these stages is about creating buffers, such as a business line of credit and adequate cash reserves, to weather inevitable ups and downs.
The Mature Stage: Shifting Focus to Wealth Preservation
As your business stabilizes and becomes profitable, your financial priorities shift from growth to preservation. The focus becomes protecting what you’ve built and reducing the risk of having your wealth concentrated in one place.
This is where systematic diversification becomes essential. We work with business owners to gradually redirect profits into assets unrelated to their company—such as diversified portfolios of stocks and bonds or real estate. This isn’t about losing faith in your company; it’s about building a financial foundation that can withstand volatility from economic downturns or industry shifts.
Managing surplus cash also becomes a key consideration. Instead of letting profits sit in low-yield business accounts, we help you deploy that capital strategically. This could involve maximizing retirement contributions, funding education accounts, or building an investment portfolio designed to generate income independent of your business.
At this stage, the planning focus broadens to include tax strategy, estate considerations, and appropriate insurance coverage. The goal is to reduce unnecessary risk and begin preparing for the eventual transition from daily ownership. At this point, your work is not only about growing the company, but about building and preserving long-term wealth.
Core Components of a Comprehensive Wealth Management Plan
When we discuss how to do wealth management for business owners, we’re addressing the full spectrum of your financial life—from tax minimization and asset protection to legacy planning and philanthropy. These components work together to create a resilient and efficient financial structure.
Tax Planning and Optimization
For business owners, tax planning is an ongoing strategy, not a year-end task. Your business structure—whether an LLC, S-Corp, or C-Corp—has direct implications for your personal tax liability. We review these structures regularly to ensure they remain optimal as your business and income grow.
Proactive tax strategies also include maximizing contributions to tax-advantaged retirement accounts (SEP IRAs, Solo 401(k)s), implementing tax-loss harvesting in investment portfolios, and strategically timing income and expenses.
Charitable giving can also be a powerful tool. A donor-advised fund, for example, allows you to make a large charitable contribution in a high-income year, receive an immediate tax deduction, and then recommend grants to your favorite charities over time. Our goal is to coordinate these strategies across your business and personal finances, working with your CPA to ensure no opportunity is missed.
Estate Planning, Trusts, and Legacy
Estate planning ensures that the assets you’ve built are transferred according to your wishes, with minimal tax burden and complexity. For business owners, this is especially critical, as the business is often the largest asset. Without a plan, your family could be forced to sell the business to cover estate taxes or settle disputes.
The foundation includes a will, healthcare directives, and powers of attorney. However, for most owners, trusts are essential tools. A revocable living trust allows assets to transfer to heirs without the delay and public process of probate. An irrevocable trust can shield assets from estate taxes and creditors by removing them from your taxable estate.
We also explore lifetime gifting strategies, such as annual exclusion gifts or family limited partnerships (FLPs), to transfer wealth to the next generation in a tax-efficient manner. The key is a customized plan that reflects your family dynamics, business succession goals, and personal values.
Using Insurance for Asset Protection
Insurance is not an investment; it’s a tool for risk management that protects what you’ve already built. For business owners, the right coverage creates a crucial safety net.
- Key person insurance protects your business if you or another critical executive can no longer work, providing funds to cover lost revenue or recruit a replacement.
- Buy-sell agreements, often funded by life insurance, provide a clear, funded plan for the remaining owners to purchase a departing owner’s share in the event of death or disability.
- Disability insurance replaces your income if you’re unable to work, reducing pressure to draw from business reserves or personal investments.
- Umbrella liability policies offer an extra layer of protection against large claims or lawsuits that could threaten your personal assets.
Securing adequate insurance is about prudent risk management. It allows you to focus on growth, knowing you are protected against events that could otherwise derail your progress.
Navigating the Exit: Succession and Post-Sale Wealth Management
For most business owners, a company represents more than a financial asset; it’s a significant part of their identity. When it’s time to step away, the emotional weight can match the financial complexity. A successful exit is often the result of planning that began years earlier.

The process of selling a business can be challenging, with many companies listed for sale not resulting in a completed transaction. Many owners discover later in the process that their business may not be valued as they expected, or that taxes will materially affect the net proceeds from the sale.. This is why how to do wealth management for business owners during the exit phase is so critical.
Pre-Exit Planning: How to do wealth management for business owners before a sale
The most valuable work happens long before a buyer appears. We recommend beginning serious exit planning at least three to five years before your target date. This provides time to implement strategies that can materially improve your business’s value and your after-tax proceeds.
The first step is clarifying your personal objectives. What does life after the business look like? How much do you need, after taxes, to fund that life? A professional business valuation provides a realistic baseline and helps identify areas for improvement, such as strengthening your management team or diversifying your customer base.
Tax planning for the sale is where early action creates the most value. The structure of the sale—stock versus asset—has major tax implications. If your business qualifies for Qualified Small Business Stock (QSBS) treatment, you may be able to exclude a significant portion of capital gains from federal taxes. Many owners don’t realize that once you sign a Letter of Intent (LOI) with a buyer, many tax and estate planning opportunities close. Strategies like Grantor Retained Annuity Trusts (GRATs) or strategic gifts work best when implemented years, not months, before a sale.
Post-Exit Strategies: How to do wealth management for business owners after a liquidity event
Selling your business fundamentally changes your financial situation. You’ve converted years of concentrated work into liquid capital, and this transition requires a new approach to wealth management.
The immediate priority is creating a diversified investment plan. Your wealth is no longer tied to a single illiquid asset. Now, the goal is to build a portfolio that balances growth with risk management across multiple asset classes, geographies, and strategies. We focus on creating portfolios that offer liquidity, transparency, and tax efficiency.
Your insurance and estate planning documents must also be reviewed and updated to reflect your new asset structure and net worth. This is an essential step in protecting what you’ve built.
Many owners feel energized after an exit and are ready for new ventures or philanthropic goals. Some launch new businesses, invest in startups, or join boards. Others focus on charitable causes, using tools like donor-advised funds to create structured, tax-efficient giving strategies. The post-exit phase is about redefining your relationship with wealth and designing a life that aligns with your values, supported by a durable financial foundation.
Frequently Asked Questions about Wealth Management for Business Owners
Business owners often share similar concerns about building security while running their companies. Here are answers to the questions I hear most often.
How early should a business owner start wealth management?
From day one. The moment you launch your business, your financial life becomes more complex. Decisions made early on, such as your business entity structure, have lasting consequences.
Starting early means establishing the right legal structure to protect personal assets, opening separate bank accounts, and maintaining clear financial boundaries. It also means setting up a retirement account—even with small initial contributions—to build the discipline of paying yourself consistently. These foundational habits create a much smoother path to long-term financial security.
What is the biggest wealth management mistake business owners make?
The biggest mistake is concentration risk—having nearly all your wealth tied up in your business while neglecting to build financial assets outside of it.
This happens because the business is often your most successful investment, making it tempting to reinvest every dollar. However, this creates a precarious situation where your entire financial future depends on a single, illiquid asset. This is often accompanied by neglecting personal retirement savings, assuming the business will fund retirement. A lack of a clear exit plan is another common and costly mistake.
The solution is not to stop investing in your business, but to create balance by systematically building wealth outside your company while you continue to grow it.
How do I find a wealth manager who understands business owners?
Not all wealth managers are equipped to handle the unique challenges of business ownership. When evaluating advisors, look for specific experience and a clear process.
- Seek experience with entrepreneurs. Have they guided owners through exits? Do they understand pre-sale tax planning strategies like QSBS?
- Ask about their process for illiquid assets. A good advisor will have thoughtful strategies for addressing concentration risk while respecting the realities of business ownership.
- Check their credentials. Professional certifications like CFP® (Certified Financial Planner), CFA®, or CPWA® indicate a commitment to ongoing education and high ethical standards.
- Ensure they work collaboratively. Your wealth manager should function as part of an integrated team with your CPA and attorney, ensuring all your advisors are working toward the same goals.
At Acadia Wealth Advisors, our practice is built around understanding how to do wealth management for business owners. We know your situation requires a partner who understands the unique challenges and opportunities that come with owning a business.
Conclusion: Securing Your Life’s Work for Generations
Building a business is about more than money; it’s a testament to your vision and commitment. The transition from building wealth to preserving it requires a different set of strategies. How to do wealth management for business owners is an ongoing partnership that evolves with your business and your life.
Our work with business owners across Virginia, Georgia, Texas, and Tennessee has shown that an integrated approach is essential. Thoughtfully separating business and personal finances, diversifying beyond your company, and proactively planning for taxes and estate transitions are the foundations of lasting financial security.
Too often, owners realize late in the process that they have missed key opportunities. The good news is that it’s never too late to start planning. Every step you take today builds a stronger foundation for tomorrow.
At Acadia Wealth Advisors, we are committed to being your trusted partner through every stage of this journey. Our data-driven approach focuses on what matters most: stable growth, accessible funds, and the confidence that your life’s work will benefit your family and community for generations to come.
Take the next step in your journey by exploring our approach to Wealth Transfer and Legacy Planning.