

Why Estate Planning is Crucial for Young Families
Holding your child for the first time changes everything. Your priorities shift, and protecting their future becomes paramount. Yet, thinking about a future where you’re not there is a topic many parents avoid.
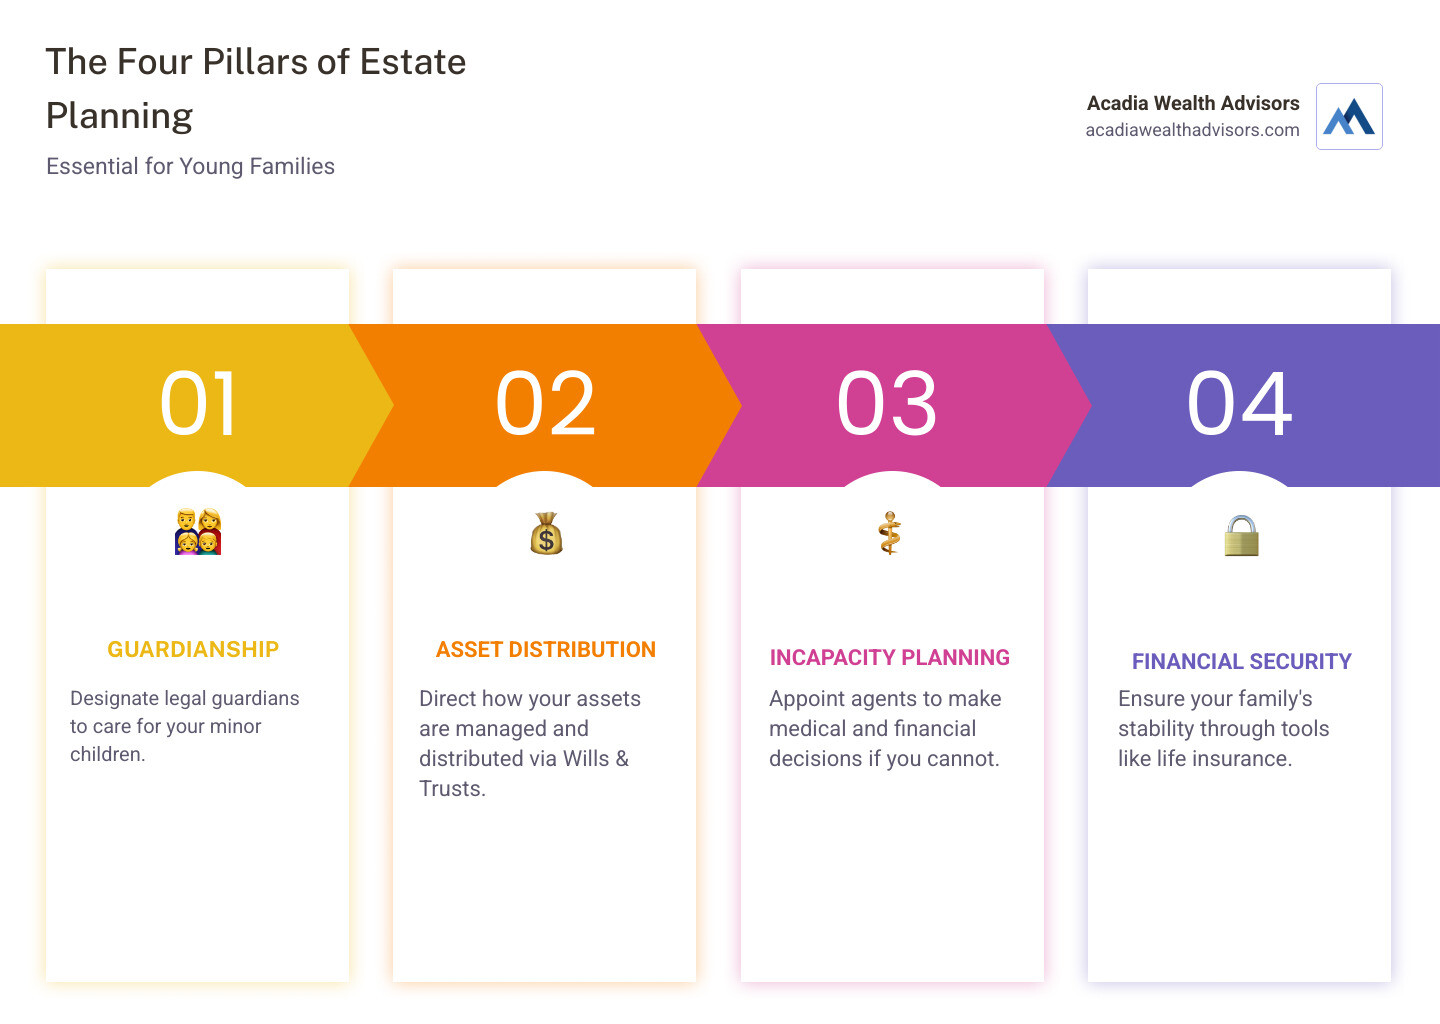
Estate planning for young families is about building a safety net for your children’s future. It ensures they are cared for and financially secure, no matter what happens to you. It involves key legal documents and financial strategies:
- Guardianship: Naming trusted individuals to care for your children if you’re gone.
- Wills and Trusts: Directing how your assets are managed and distributed.
- Incapacity Planning: Appointing people to make medical and financial decisions if you cannot.
- Life Insurance: Providing financial support to your family when they need it most.
A recent survey shows that just 36 percent of parents with kids under 18 have a will. This guide demystifies estate planning with simple, actionable steps to ensure your children are always protected.
As Managing Partner and Portfolio Manager at Acadia Wealth Advisors, Frank Gristina brings over 25 years of investment experience to help families steer the financial complexities of estate planning for young families. His expertise focuses on aligning financial strategies with life goals, ensuring peace of mind for clients.
When you become a parent, estate planning for young families becomes an absolute necessity to ensure your children are cared for and your assets are distributed according to your wishes. Without a solid plan, the state of Virginia has predetermined guidelines for how your estate will be distributed if you pass away (“dying intestate”). These generic state laws rarely align with a family’s unique wishes, which can lead to court-appointed guardians, lengthy probate, and family disputes. We believe in empowering families to take control of their legacy, a cornerstone of effective Wealth Transfer and Legacy Planning.
The Risks of Having No Plan
Without an estate plan, a judge who doesn’t know your family will make critical decisions for your children. This can lead to:
- Losing control over asset distribution: Your assets might not go to the people you intend. State law dictates distribution, which could mean children receive their inheritance outright at 18, regardless of financial maturity.
- Court deciding guardianship: A court, not you, will appoint a guardian for your minor children. This can lead to custody battles or even temporary placement in foster care.
- Lengthy and public probate: The legal process to distribute assets can be prolonged, expensive, and public, tying up funds for months or years.
- Financial hardship for survivors: Without clear instructions, your family could face immediate financial strain while waiting for assets to be released.
- Unnecessary taxes and fees: A well-structured plan can minimize estate taxes and fees, ensuring more of your wealth goes to your loved ones.
What Happens if You Become Incapacitated?
Estate planning also prepares for potential incapacitation from an accident or illness. Without proper legal documents in place:
- Inability to make decisions: You cannot communicate your wishes for medical care or financial affairs.
- Court intervention: A court may appoint a conservator to make decisions for you. This process is invasive, time-consuming, and the person appointed may not be your choice.
- Financial accounts frozen: Your family might struggle to access funds to pay bills or manage household finances.
- Medical decisions made by others: Loved ones may be forced to make difficult medical decisions without knowing your preferences, adding to their burden.
- Added stress on family members: Navigating these challenges without a plan creates significant stress and conflict for your family.
The Essential Components of Your First Estate Plan
Building your first estate plan doesn’t have to be overwhelming. For young families, it comes down to a handful of essential documents that create a safety net for your loved ones.
At its core, estate planning for young families involves five key components: a Will to state who gets your property and who will care for your children; a Trust to manage assets for beneficiaries; Powers of Attorney to handle decisions if you’re incapacitated; a Healthcare Directive to outline medical wishes; and Beneficiary Designations on accounts like life insurance and retirement funds to pass assets directly to recipients, skipping probate.
These components work together to give you control over your family’s future, rather than leaving those decisions to the courts, as noted in Essential Estate Planning for Young Adults.
Why a Will is the Cornerstone of Estate Planning for Young Families
If you do nothing else, create a will. For parents, this document is vital because it’s where you name guardians for your minor children. This is your chance to choose someone who shares your values and parenting philosophy. Without a will, a Virginia court makes this deeply personal decision for you.
Your Last Will and Testament also lets you name an executor—the person you trust to handle your estate, pay debts, and distribute assets. The will also lets you distribute your property according to your wishes and can express your final wishes on matters like funeral arrangements, providing guidance to your loved ones during a difficult time.
Powers of Attorney: Planning for Incapacity
Many young parents don’t consider what happens if they’re alive but unable to make decisions. A sudden illness or accident could leave you incapacitated, which is where powers of attorney become essential.
A Durable Power of Attorney for finances appoints an agent to manage your financial affairs if you can’t. This person can pay your mortgage, manage bank accounts, and keep your household running financially. Without it, your family would need to petition the court to gain access to your accounts.
The Healthcare Power of Attorney designates an agent to make medical decisions on your behalf when you’re unable to communicate. This person speaks for you with doctors and ensures your healthcare wishes are honored. In Virginia, this document gives your agent clear legal authority, sparing your family from guessing what you would have wanted during a medical crisis.
Will vs. Trust: What’s the Right Choice for You?
As you explore estate planning for young families, you’ll hear about wills and trusts. Both are valuable tools, but they work differently.
A will is typically less expensive to create and is essential for naming guardians. However, it must go through probate, a public court process that can be lengthy and tie up your assets.
A revocable living trust, on the other hand, avoids probate. Assets in the trust pass directly to your beneficiaries privately and quickly. The trust also provides seamless management if you become incapacitated, with your successor trustee stepping in without court involvement.
Here’s how they compare:
| Feature | Will | Revocable Living Trust |
|---|---|---|
| Probate Avoidance | Generally required (public, can be lengthy and costly) | Avoids probate (private, faster asset distribution) |
| Privacy | Becomes public record during probate | Remains private |
| Cost to Set Up | Generally less expensive upfront | Typically more expensive upfront |
| Management During Incapacity | Does not provide for incapacity management; requires separate Durable Power of Attorney or court-appointed conservator | Provides seamless management of trust assets if you become incapacitated |
| Control Over Asset Distribution for Children | Assets distributed outright at legal age (18 in Virginia) unless a testamentary trust is created within the will | Allows for staggered distributions at specific ages or milestones, and can hold assets for special needs children |
| Amendment | Can be easily amended or revoked | Can be easily amended or revoked during your lifetime |
For most young families in Virginia, starting with a will is the right first step. As your estate grows or if you want more control over how your children receive their inheritance (e.g., at ages 25, 30, and 35 instead of all at 18), a revocable living trust becomes increasingly valuable.
Many families use both. A “pour-over will” works with a living trust, ensuring any assets not already in the trust’s name automatically transfer into it. This combination provides the guardianship benefits of a will with the probate avoidance of a trust. We help families determine which approach makes the most sense for their unique circumstances and goals.
Securing Your Children’s Future: An In-Depth Look at Estate Planning for Young Families
Everything we’ve discussed comes together here, at the heart of estate planning for young families: securing your children’s future. You’re not just protecting assets; you’re protecting college dreams and the life you’ve imagined for your kids. This means getting serious about guardianship, life insurance, and how your children will inherit. These pieces work with your broader financial picture, including Retirement Planning, because protecting your family’s future is about protecting all your long-term goals.
How to Choose the Right Guardian for Your Children
Choosing a guardian is difficult, but it’s one of the most loving things you can do for your kids. You’re picking someone to step into your shoes and raise your children with the same love and values you would.
Start by thinking about shared values and parenting style. Will this person raise your children with similar beliefs about education, faith, and discipline? Also consider their financial stability, age, and health. A guardian who is financially sound and healthy can offer a more stable environment. Location is another factor. Would your children need to move away from their school and friends?
Most importantly, talk to them first. You must have an open conversation with potential guardians before naming them in your will, as this is a massive responsibility. Always name at least one alternate guardian, because life changes and your first choice might not be available. 64% of parents with young children are leaving this critical decision to a Virginia court.
The Role of Life Insurance in Your Financial Safety Net
For most young families, life insurance is essential. It’s the financial bridge that keeps your family afloat if you’re suddenly not there to provide for them. Life insurance replaces lost income, giving your surviving spouse breathing room to grieve without immediate financial panic. It covers debts and your mortgage, potentially allowing your family to stay in their home, and funds education.
The good news? Term life insurance is remarkably affordable for young, healthy people. It provides coverage for a specific period, usually 20 or 30 years, which aligns with the years your children depend on your income. While whole life insurance offers lifelong protection, term life often gives young families the most coverage when they need it most. We typically suggest clients consider coverage between $1 million and $2 million, though your specific needs depend on your family’s situation.
Using Trusts in Estate Planning for Young Families
If a will is the foundation of estate planning for young families, trusts provide control over your children’s inheritance. Minor children cannot legally inherit assets directly. If you leave money to a child through a will, a court will appoint someone to manage it until they turn 18, at which point they get everything at once. Most 18-year-olds aren’t ready for that responsibility.
A Revocable Living Trust is created while you’re alive and can be changed anytime. You serve as the initial trustee, and if you pass away, your successor trustee steps in seamlessly. Assets in this trust avoid probate, staying private and becoming available to your family much faster. A Testamentary Trust is created within your will and only activates after your death. It still goes through probate but provides structured management for the inheritance.
The trustee you appoint manages the trust’s assets according to your instructions. Many parents wisely separate the guardian role from the trustee role to create healthy checks and balances. Trusts also protect assets from creditors and allow you to set up staggered distributions, releasing funds at ages or milestones you choose.
For families with a child who has special needs, a Special Needs Trust is critical. It provides financial support without jeopardizing eligibility for government assistance like Medicaid or SSI. An ABLE account is another excellent tax-free savings option for individuals with disabilities. At Acadia Wealth Advisors, we help families steer these complex decisions, ensuring your plan truly protects your children’s future.
Maintaining Your Plan: A Lifelong Process
Creating an estate plan isn’t a one-and-done task. It’s more like tending a garden—it needs regular attention to thrive. Your life isn’t static, and neither should your estate planning for young families be.
Think about how much has changed since you first became a parent. Maybe you’ve had another child, bought a bigger home, or changed careers. These shifts are signals that your estate plan needs a fresh look. The families we work with feel relieved knowing their plan can grow with them. This proactive approach is central to comprehensive Estate Planning, ensuring your family’s protection adapts as your circumstances evolve.
Key Life Events That Trigger a Review
Some moments in life are so significant they should automatically send you back to your estate planning documents.
- The birth or adoption of a child is the biggest trigger. You need to revisit guardianship, adjust life insurance, and possibly establish new trusts.
- Marriage or divorce fundamentally changes your family structure and requires updating beneficiaries, agents, and potentially guardianship.
- A significant change in assets—like buying a home, starting a business, or receiving an inheritance—means your distribution plan might need adjusting.
- Moving to a new state matters because estate laws vary. If you relocate to or from Virginia, your documents may need updates to comply with local laws.
- The death of a beneficiary or guardian requires you to designate new individuals. Similarly, changes in health might necessitate adjustments to healthcare directives or special needs planning.
How Often Should You Review Your Plan?
We recommend reviewing your estate plan every three to five years, even if nothing dramatic has happened. Of course, any major life event should trigger an immediate review.
During these reviews, consulting with professionals is key. Your estate planning attorney and financial advisor can help you understand changes in tax laws, Virginia state regulations, or financial strategies.
Keeping documents updated extends beyond your will and trust. Your beneficiary designations on life insurance policies and retirement accounts must align with your overall plan.
Finally, communicating with family helps everyone understand their roles. Discussing your intentions with chosen guardians, executors, and agents prevents confusion and surprises down the road. Your estate plan is a living reflection of your family’s story; as that story unfolds, your plan should evolve with it.
Conclusion: Take Control of Your Family’s Future

Becoming a parent is an incredible journey, filled with boundless love and a deep desire to protect your little ones. We understand that thinking about “what if” scenarios can be tough, but taking these proactive steps in estate planning for young families isn’t just a legal formality—it’s a profound act of love. It’s about ensuring your legacy is one of unwavering protection and care, providing security and long-term peace of mind, no matter what life brings.
A well-crafted estate plan is the ultimate expression of this love. It’s your way of saying, “I’ve got you, always,” even when you can’t be there physically. It safeguards your children’s future, secures their inheritance, and ensures their well-being is in the hands of people you trust implicitly.
To build a comprehensive strategy that’s custom-fit to your family’s unique needs, consider partnering with a trusted financial advisor. Here at Acadia Wealth Advisors, with deep roots across Virginia—including Charlottesville, Richmond, Alexandria, Roanoke, and Lynchburg—we truly understand the unique challenges and opportunities that young families face.
Our data-driven guidance is designed to help you steer these important decisions with clarity and confidence, aiming for stable growth, accessible funds, and multi-generational wealth transfer. Don’t leave your family’s future to chance. We’re here to help you steer these complex decisions, ensuring your plan truly protects what matters most. Start securing your family’s future today by exploring your Estate Planning options and contacting us to begin crafting a plan that brings you true peace of mind.