

Why Multi-Generational Wealth Planning Matters Now More Than Ever
Estate planning for multi-generational wealth transfer is the strategic process of preserving and passing wealth across three or more generations. A successful plan minimizes tax impact, prepares heirs, and maintains family harmony. Key components include:
- Clear Communication – Open dialogue about wealth goals and expectations.
- Strategic Legal Structures – Using trusts and foundations to protect assets.
- Financial Efficiency – Leveraging exemptions and strategies to minimize tax impact.
- Heir Preparation – Financial education to ensure readiness for stewardship.
- Values Alignment – A family mission statement to guide decisions.
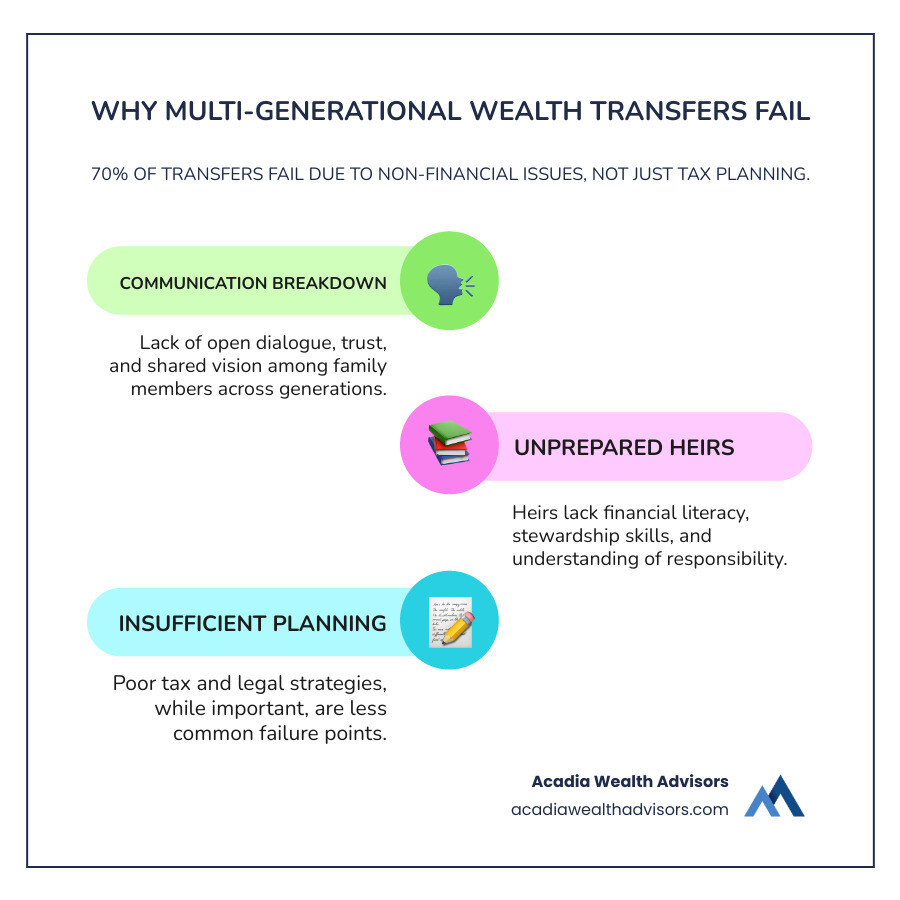
We are in the midst of the largest intergenerational wealth transfer in history. A historic amount of assets will pass from Baby Boomers to younger generations. However, studies show a high failure rate for these transfers. This is not usually due to poor technical planning, but rather a breakdown in communication, unprepared heirs, and a lack of shared family vision.
The stakes are high. Without a thoughtful plan, family businesses could be liquidated, legacies squandered, and family harmony fractured. A comprehensive approach addresses both the technical and human elements, combining legal structures like dynasty trusts with the critical work of family communication and financial education. It recognizes that preserving wealth requires preparing people to be wise stewards.
This guide covers the pillars of multi-generational wealth planning: defining goals, understanding legal and financial tools, navigating the tax landscape, and preparing your heirs.
I’m Frank Gristina, Managing Partner of Acadia Wealth Advisors. With over 25 years of experience, I’ve learned that effective planning requires both technical precision and a deep understanding of family dynamics. My approach integrates long-term investment strategy with comprehensive wealth planning to help families build legacies that endure.
Defining Your Legacy: The Goals and Values of Multi-Generational Wealth Transfer
When families approach us for estate planning for multi-generational wealth transfer, our first question is: What do you want your wealth to accomplish? This question goes beyond moving assets; it’s about ensuring your wealth serves your family’s priorities for decades.
While wealth preservation and asset growth are essential, most families are also concerned with more personal goals. They want to maintain family harmony, ensure their children handle wealth responsibly without losing their work ethic, and use their resources to make a positive impact. These are the questions that shape a meaningful legacy. At Acadia Wealth Advisors, we find that the most successful transfers occur when families articulate not just what they are passing down, but why.
The Crucial Role of Communication and a Shared Vision
The high failure rate of wealth transfers is primarily caused by a breakdown in communication and unprepared heirs. Families that avoid open conversations about wealth, expectations, and values are setting the stage for future conflict.
Talking about money and mortality can be uncomfortable. Parents may worry about creating dependency, while adult children might feel awkward asking about inheritance. However, avoiding these conversations only postpones them to a more difficult time—often after you are gone and cannot provide clarity.
Regular family meetings create a space for open discussion and trust-building. They allow you to explain the reasoning behind your decisions, such as why distributions are structured in a certain way. When heirs understand the why, they are more likely to accept the plan. This open communication also helps prepare them for their future responsibilities, as financial literacy develops through ongoing conversation and involvement.
How to Align Your Wealth Transfer Plan with Your Family’s Core Values
Your wealth plan should reflect your beliefs. Many families focus on financial efficiency but neglect to align their plans with their deeper values. Start by identifying your family’s shared values: Education? Entrepreneurship? Philanthropy? Financial independence? These should actively shape how your wealth is structured.
A family mission statement can serve as a constitution, articulating your purpose and vision for how wealth should be used. This document guides trustees and family members, reminding them of what matters beyond the balance sheet.
When you integrate these values into your legal documents, your wealth becomes a tool for impact. For example, if education is a core value, your trusts might prioritize funding for college or vocational training. If you value entrepreneurship, you could structure support for family members starting businesses. This alignment is key to creating a meaningful legacy.
To learn more about how we help families integrate their values into comprehensive planning, visit our Estate Planning services page.
The technical structures we’ll discuss next work best when built on this foundation of clear goals, open communication, and shared values.
The Planner’s Toolkit: Key Structures for Estate Planning for Multi-Generational Wealth Transfer
Once your family’s goals are clear, the next step is selecting the right legal structures. These tools are the building blocks of your legacy, designed to protect assets, minimize tax impact, and ensure your wishes are honored. The right combination depends on your unique situation, which is why a customized plan is essential.
Understanding Trusts for Long-Term Control and Protection
Trusts are the workhorses of estate planning for multi-generational wealth transfer. They are legal arrangements where you (the grantor) transfer assets to a trustee, who manages them for your beneficiaries according to your instructions. Trusts offer control beyond the grave, allowing you to specify how and when wealth is distributed, while also providing protection from creditors, divorce, and certain tax liabilities.
- Dynasty Trusts are designed to last for multiple generations, shielding assets from certain transfer taxes for as long as state law allows.
- Generation-Skipping Transfer (GST) Trusts are designed for transfers to grandchildren or younger generations, helping to preserve wealth by minimizing the impact of transfer taxes across multiple generations.
- Spousal Lifetime Access Trusts (SLATs) allow one spouse to create an irrevocable trust for the other, removing assets from the grantor’s taxable estate while the beneficiary spouse can still access the funds if needed.
- Irrevocable Life Insurance Trusts (ILITs) hold life insurance policies outside of your taxable estate. The death benefit can then pass to heirs efficiently, providing liquidity for estate expenses or other needs.
- Grantor Trusts are structured so that the grantor pays the income taxes on the trust’s earnings. This allows the trust assets to grow without being diminished by taxes, which can be a powerful way to transfer more wealth while also reducing the grantor’s taxable estate.
A critical, often overlooked decision is trustee selection. For long-term trusts, we often recommend professional trustees for their continuity, impartiality, and expertise, as noted in this multidisciplinary approach to philanthropy and multigenerational trusts.
Using Family Foundations and Philanthropy to Build a Legacy
Charitable giving is about more than financial benefits; it’s a way to unite your family around shared values and teach stewardship.
- Donor-Advised Funds (DAFs) offer a simple way to engage in philanthropy. You contribute assets, receive potential tax advantages, and then recommend grants to charities over time. DAFs are excellent for involving younger family members without the administrative burden of a foundation.
- Private foundations offer complete control over investment strategy and grant-making. They are ideal for families with significant wealth and a deep commitment to creating a lasting charitable legacy that can span generations.
Involving younger generations in philanthropy provides a training ground for financial stewardship. The financial benefits can be substantial, but more importantly, philanthropy helps answer the question: What kind of legacy do you want to leave?
To explore how charitable strategies can be woven into your comprehensive wealth plan, visit our Wealth Transfer and Legacy Planning page.
Understanding the Financial Landscape: Tax Mitigation and Transfer Methods
Many families feel overwhelmed by the tax implications of wealth transfer. Understanding the financial landscape of estate planning for multi-generational wealth transfer is about protecting what you’ve built so more of your legacy reaches the people and causes you care about.
In the U.S., the primary federal taxes are the estate, gift, and generation-skipping transfer (GST) taxes. Currently, each U.S. citizen has a substantial federal exemption. However, under current law, this high exemption is temporary and scheduled to be significantly reduced in 2026. Assets above this threshold will be subject to a significant federal tax. This upcoming change creates a critical window for strategic planning.
Comparing Common Wealth Transfer Methods
Different transfer methods offer different levels of control, tax efficiency, and protection.
- Outright gifts are simple but offer no ongoing control. The recipient receives full ownership, and the assets are exposed to their creditors or potential divorce. Gifts above the annual exclusion use up your lifetime exemption.
- Joint tenancy with right of survivorship is common for real estate and bank accounts. It avoids probate but offers limited control, as the joint owner has access to the assets. It can also create gift tax issues and may not remove the asset from your taxable estate.
- Beneficiary designations on retirement accounts and life insurance policies are simple and effective. They bypass probate and allow you to retain full control during your lifetime.
- Transfers in trust provide the most control and protection. You set the terms for how assets are managed and distributed. Irrevocable trusts can remove assets from your taxable estate, protect them from beneficiaries’ creditors, and avoid probate.
Key strategies for tax mitigation in estate planning for multi-generational wealth transfer
We use several practical strategies to minimize tax burdens:
- Annual exclusion gifting: You can give a certain amount to any number of individuals each year free of gift tax and without using your lifetime exemption. This can be a simple and powerful way to transfer significant wealth over time.
- Lifetime exemption gifting: With the exemption set to decrease, using your current, higher exemption now is a “use-it-or-lose-it” opportunity to lock in the benefits of the current exemption.
- Valuation discounts: Gifting minority interests in private businesses or real estate can allow you to transfer more value while using less of your gift tax exemption, as these interests are often valued at a discount.
- Strategic use of grantor trusts: In certain trusts, the grantor pays the income tax on the trust’s earnings. This allows the trust assets to grow without that tax burden, effectively increasing the amount passed to beneficiaries and further reducing the grantor’s estate.
- Paying tuition and medical expenses directly: Payments made directly to an educational institution or healthcare provider for someone else are not considered taxable gifts and do not use up any of your exemptions.
For more on advanced techniques, the American Bar Association offers insights on Generation-Skipping Transfer Tax Planning Opportunities.
Navigating Cross-Border Planning (Canada & U.S.)
For families with ties to both the U.S. and Canada, planning is more complex. Canadians who own U.S.-situs property (like U.S. real estate or stocks) can face U.S. estate tax. The U.S.-Canada Tax Treaty provides relief by allowing Canadians to claim a portion of the U.S. exemption. However, as the U.S. exemption is scheduled to decrease, this benefit will also be reduced.
The two countries have different tax systems. Canada has deemed disposition rules at death that trigger capital gains taxes, rather than an estate tax. These systems must be carefully coordinated to avoid unintended tax consequences. We work with cross-border specialists to create efficient plans for families in this situation.
For more on how we help high-net-worth families steer complex financial situations, visit our page on Financial Planning for High Net Worth Individuals.
Beyond the Balance Sheet: Preparing Heirs and Building a Lasting Legacy
The best legal and tax strategies will fail if the next generation isn’t ready to receive wealth. A primary reason for the high failure rate in wealth transfers is due to heirs being unprepared for their responsibilities. At Acadia Wealth Advisors, we believe estate planning for multi-generational wealth transfer must focus as much on preparing people as it does on preparing portfolios. The goal is to cultivate wise stewards, not just transfer assets.
How to effectively prepare the next generation for wealth stewardship
Financial literacy is built gradually through education, dialogue, and experience. Successful families often prepare their heirs by:
- Starting education early with age-appropriate concepts, like saving for a ten-year-old or investing for a teenager.
- Making money an open conversation rather than a family secret. This helps manage expectations and prepares heirs for future discussions about the family’s wealth and its purpose.
- Providing hands-on experience. Involving heirs in meetings with financial advisors, creating a family investment club, or including them in charitable giving decisions builds real-world competence and confidence.
- Arranging mentorship with trusted advisors or family members who can model responsible wealth stewardship.
The goal is to foster a mindset of stewardship rather than entitlement. Heirs should understand that family wealth is a resource they are responsible for managing, growing, and passing on. This perspective is what separates families who preserve wealth for generations from those who do not.
The role of philanthropy in estate planning for multi-generational wealth transfer
Philanthropy is a powerful tool for preparing heirs. When families engage in charitable giving together, it provides a training ground for financial decision-making while reinforcing family values. Discussing which causes to support teaches critical thinking and values-based analysis in a supportive environment.
Charitable work can also be a unifying force, shifting the family’s focus from “what am I getting?” to “what are we accomplishing together?” It helps create a legacy that extends beyond financial wealth, giving deeper meaning and purpose to the assets you’ve accumulated.
Donor-advised funds (DAFs) are a flexible starting point for involving younger generations, while private foundations offer more control for families with a deeper philanthropic commitment. Integrating philanthropy into your estate planning for multi-generational wealth transfer can be an effective part of your overall financial strategy, teaching valuable skills, strengthening family bonds, and creating a lasting positive impact.
To learn more about how we help families integrate charitable giving into their comprehensive wealth plans, visit our page on Wealth Transfer and Legacy Planning.
Frequently Asked Questions about Multi-Generational Wealth Transfer
How early should our family start planning for wealth transfer?
The best time to start is as soon as you have accumulated significant wealth. Estate planning for multi-generational wealth transfer is not a one-time event but an ongoing process that should evolve with your family and financial situation. Starting early provides more time for tax-efficient strategies to compound and for the next generation to develop the financial literacy needed to manage wealth wisely. We integrate wealth transfer planning into our clients’ broader financial strategy from the beginning.
What is the single biggest mistake families make?
The most common reason wealth transfers fail is not a technical error but a breakdown in family communication and trust. The second leading cause is heirs who are unprepared to manage the wealth they receive. These “softer issues” are often more damaging than any tax planning mistake. A plan is only as strong as the people who are part of it, which is why we emphasize open dialogue and heir preparation.
Can a multi-generational wealth transfer plan be changed?
Yes, and it should be. A good wealth transfer plan is a living document. Life changes, families evolve, and tax laws shift. We recommend reviewing your plan every few years and after any major life event, such as a birth, death, marriage, or divorce. The scheduled reduction in the federal estate tax exemption is a perfect example of why regular reviews are critical to ensure your plan continues to reflect your goals.
Conclusion: Building a Legacy That Lasts
We’ve covered the essential elements of a lasting legacy, from defining your values and preparing your heirs to choosing the right legal structures and navigating the tax landscape. Successful estate planning for multi-generational wealth transfer is about more than protecting assets; it’s about purpose and preparedness.
The families who build enduring legacies understand this. They take the time to have important conversations about money and expectations, and they invest in preparing the next generation to be wise stewards. The technical tools—like dynasty trusts and family foundations—are most effective when grounded in clear family values and supported by open communication. This is how families overcome the high failure rate, which is most often caused by a breakdown on the human side of the equation.
Your wealth represents years of hard work and deserves a plan that honors that effort. At Acadia Wealth Advisors, we help families across Virginia, Georgia, Texas, and Tennessee steer these complexities. Our approach integrates data-driven investment strategies with comprehensive wealth planning, always centered on your family’s unique goals. We help you build a legacy that reflects not just what you’ve accumulated, but who you are.
To learn more about our approach, visit our Wealth Transfer and Legacy Planning and About Us pages. Your legacy is waiting to be built; let’s ensure it’s one that lasts.