

Essential Financial Planning for Young Families: Building Your Foundation
What are the fundamental steps for financial planning for young families?
- Budgeting: Create a realistic and adaptable budget to manage new expenses.
- Protection: Secure essential insurance (life, disability) and legal documents (wills, power of attorney).
- Saving: Build an emergency fund and save for long-term goals like education and retirement.
- Communication: Discuss finances openly and involve family in planning.
Starting the journey of financial planning for young families is an exciting, yet often overwhelming, step. The financial responsibilities are significant, with the estimated cost of raising a child to age 18 now over $310,000. This guide will help you build a strong financial foundation for your family’s future.
As Managing Partner at Acadia Wealth Advisors, I bring over 25 years of investment experience to guide families through this journey. My goal is to provide data-driven strategies that help you steer life’s changes and build lasting security.
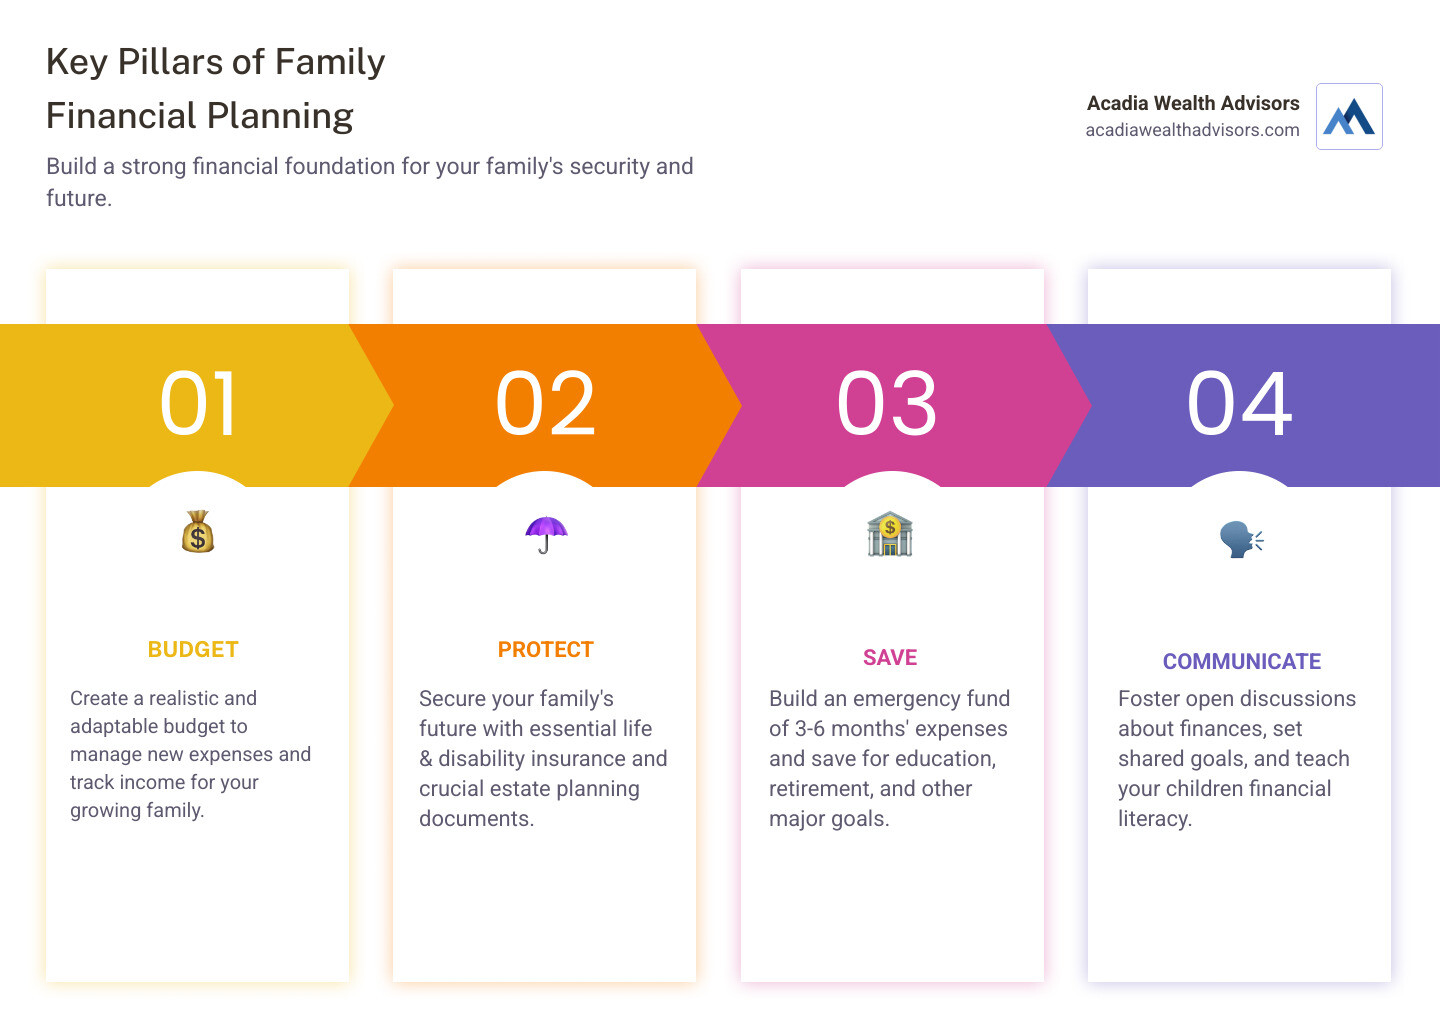
A solid financial foundation provides the stability needed to handle unexpected challenges. At Acadia Wealth Advisors, we offer personalized wealth management strategies to meet your family’s unique needs. Foundational steps like budgeting, building an emergency fund, and understanding tax benefits are essential for managing the costs of family life. If you’re looking for comprehensive support, we offer a range of services to help you. More info about our financial planning services.
Creating a Realistic Budget for Your Growing Family
The arrival of a child brings new expenses that can dramatically shift your finances, costing between $21,000 to $52,000 in the first year alone. This makes a realistic budget a critical component of financial planning for young families.
A budget is a living document that reflects your family’s priorities. Start by tracking your net income and spending. Many families find the 50/30/20 rule helpful: 50% of income for needs, 30% for wants, and 20% for savings and debt repayment. Apps like Mint or PocketGuard can help you stay in control. As your family’s needs change, your budget must evolve. Regular family meetings to review the budget can help keep everyone on the same page.
If you’re finding it challenging to create a budget that works for your family, we can help. Contact us for a personalized family budget review.
Building and Maintaining Your Emergency Fund
Life can bring unexpected financial shocks like job loss or medical bills. A robust emergency fund is an indispensable safety net in financial planning for young families, protecting you from high-interest debt.
The general recommendation is to save three to six months’ worth of essential living expenses. For single-earner households or those with variable incomes, aiming for six months or more provides greater peace of mind. To build your fund, set up automatic transfers to a dedicated, high-yield savings account. This money must be liquid—easily accessible without penalties—so investments like stocks are not suitable. Consistent saving, even in small amounts, will allow your fund to grow steadily.
Managing Childcare Costs and Tax Benefits
Childcare is a significant expense, but tax benefits can help. Two key federal options are the Child and Dependent Care Credit and a Dependent Care Flexible Spending Account (FSA).
The Child and Dependent Care Credit can cover a percentage of childcare costs, offering a maximum credit of $1,050 for one child or $2,100 for two or more. A Dependent Care FSA is often more powerful, allowing you to set aside up to $5,000 in pre-tax money for childcare expenses, lowering your overall tax bill. You generally cannot use both benefits for the same expenses, and FSAs have a “use it or lose it” rule, meaning funds must be spent within the plan year.
Beyond federal benefits, explore eligible state tax credits in Virginia to further reduce your tax liability. A tax advisor can help you determine the best strategy for your family. We can help you steer these complex rules to maximize your savings. Learn more about maximizing your family’s tax benefits.
Protecting Your Family’s Future: Insurance and Estate Planning
Comprehensive financial planning for young families means creating safeguards for the future, no matter what life brings. This involves securing the right insurance and putting an estate plan in place.
While not the most cheerful topics, life insurance, disability insurance, wills, and trusts are a critical safety net. They ensure that if the unexpected happens, your family’s financial well-being is secure and your wishes are followed. This planning provides immense peace of mind, knowing your loved ones are cared for.
The Importance of Life and Disability Insurance
Life and disability insurance act as income replacement, providing vital support when it’s needed most. This ensures your family can maintain their lifestyle and pursue their dreams, even if a primary earner can no longer contribute.
Life insurance is essential once you have dependents. It provides a tax-free sum to your beneficiaries to cover living costs, pay off a mortgage, or fund college. Many experts suggest coverage of 10 times your annual income, often $1 million to $2 million for young families.
There are two main types of life insurance:
- Term Life Insurance: This covers you for a set period (e.g., 20 or 30 years). It’s affordable and ideal for covering the years when your children are growing and expenses are highest.
- Whole Life Insurance: This permanent policy lasts your entire life and builds cash value over time. Premiums are higher, but it offers lifelong coverage.
Here’s a quick comparison:
| Feature | Term Life Insurance | Whole Life Insurance |
|---|---|---|
| Coverage Period | A specific time (e.g., 10, 20, 30 years) | Your entire lifetime |
| Premium Cost | Usually lower | Usually higher |
| Cash Value | Does not have cash value | Grows cash value over time |
| Purpose | Replaces income during your family’s highest-need years | Lifelong coverage, can help build wealth |
| Flexibility | Can sometimes be changed to whole life | You can borrow against the cash value |
It’s also vital to insure stay-at-home parents. Their contributions are immense, and a policy ensures the surviving parent can afford childcare and other services without financial strain.
Disability insurance is equally important, protecting your income if an illness or injury prevents you from working. It helps cover your mortgage, bills, and other household costs, keeping your family financially stable during a difficult time.
Essential Estate Planning Documents
Estate planning is a fundamental part of responsible parenting and a key piece of financial planning for young families. It ensures your wishes are followed and your loved ones are protected.
A will is the cornerstone, outlining how your assets will be distributed and, most importantly, naming a guardian for your minor children. Without a will, the courts make these critical decisions for you.
Other important documents include:
- Power of Attorney (POA): Appoints someone to make financial decisions for you if you’re incapacitated.
- Living Will (Advance Directive): Outlines your wishes for end-of-life medical care.
- Healthcare Proxy: Names someone to make medical decisions for you if you cannot.
Choosing a guardian is a top priority. You should also consider how to manage any money left to your children, perhaps through a trust. A living trust can help your family avoid probate—the often slow and expensive legal process of validating a will—ensuring assets transfer smoothly and privately.
Review and update your estate plan and beneficiary designations regularly as your life changes. We specialize in helping families in Virginia create comprehensive estate plans. More info about Estate Planning.
Smart Saving Strategies for Major Life Goals
While managing daily expenses, planning for long-term goals like retirement and college can feel distant. But for financial planning for young families, these goals need attention today. The key is compound interest, where your money earns money over time. A dollar invested today works harder than one invested ten years from now because it has more time to grow.
For example, saving $300 a month from your child’s birth could result in about $143,000 by college (at a 7% annual return). Waiting five years to start would yield only about $87,000. The challenge is balancing multiple goals—retirement, college, a down payment—with limited funds.
At Acadia Wealth Advisors, we help families in Charlottesville, Richmond, Alexandria, Roanoke, Lynchburg, and beyond create savings strategies that make sense for their unique situation. We help you prioritize to set your family up for both short-term stability and long-term prosperity. More info about Retirement Planning.
Saving for Your Child’s Education
College is expensive, with the average cost per student exceeding $36,000 per year in 2023. The good news is that starting early makes a huge difference. The most popular tool is the 529 plan, a state-sponsored account designed for education savings.
With a 529 plan, your money grows tax-free, and withdrawals for qualified education expenses (like tuition, books, and even some K-12 costs) are also tax-free. This is a significant advantage over standard investment accounts. Another perk is that anyone—grandparents, relatives, or friends—can contribute, making it a great option for gifts.
Custodial accounts (UGMA/UTMA) are another option. They offer more flexibility, as funds can be used for any expense that benefits the child. However, the money legally becomes your child’s when they reach adulthood (18 or 21), and they can use it however they wish. The tax benefits are also less certain than with a 529 plan. We can help you choose the path that fits your family’s goals. Contact us to discuss education savings options.
Prioritizing Savings: A Key Part of Financial Planning for Young Families
When financial planning for young families, you have to make choices about where your money goes first. The most common question is: “Should I save for retirement or my kids’ college?” While it may feel selfish, the clear advice is to secure your own oxygen mask first.
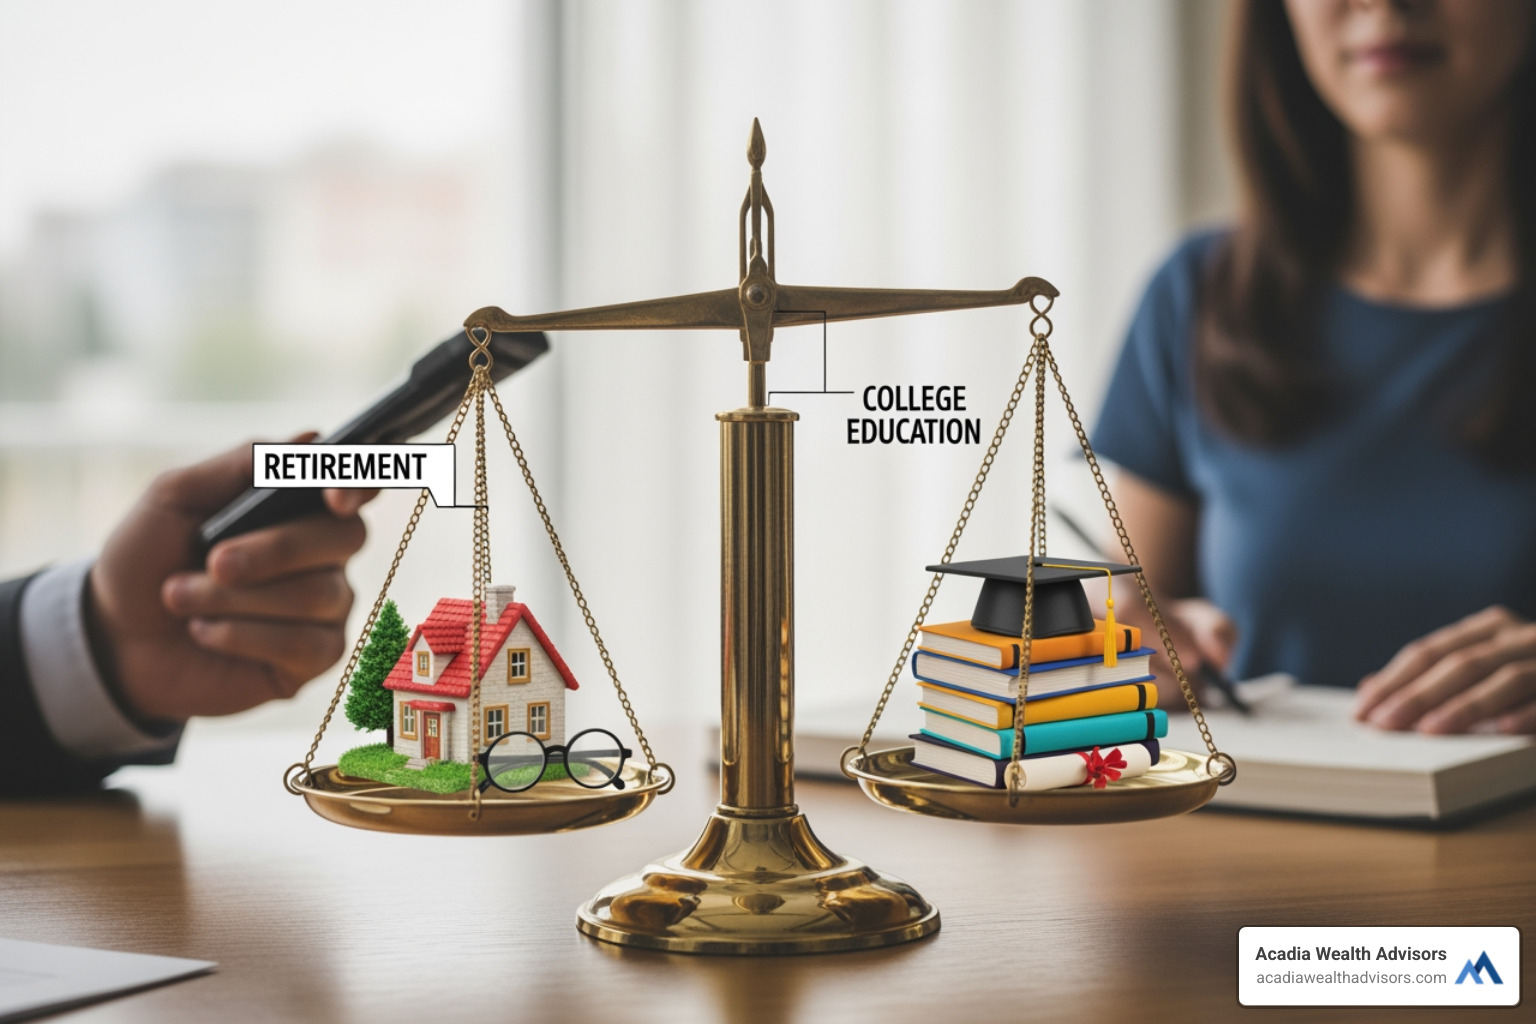
Why? Your children have options for funding college—scholarships, grants, and loans. But there are no scholarships or loans for retirement. The years you have to save are finite.
The best strategy is to “pay yourself first.” Automate contributions to your retirement accounts. At a minimum, contribute enough to your 401(k) to get the full employer match—it’s free money. After that, aim to save 10-15% of your pre-tax income for retirement.
Once your retirement savings are on track, you can direct funds toward college and other goals. An IRA (Traditional or Roth) can supplement your workplace plan and offer additional tax advantages. This approach doesn’t abandon your children’s future; it strengthens it. A financially secure parent is in a better position to help their adult children, and your children won’t face the burden of supporting you in retirement. We can help you create a strategy that supports all your goals.
The Power of Family Financial Communication
According to a study from Empower, 62% of Americans don’t talk about money. For young families building a future, these conversations are essential. Open communication about finances isn’t about awkward meetings; it’s about creating a family culture of trust and transparency where you can share goals, values, and concerns.
When you talk openly, you reduce stress, prevent misunderstandings, and build a stronger financial foundation. Financial planning for young families is most effective when everyone understands the “why” behind your decisions. Studies show that families who discuss money regularly have better financial outcomes. A study on money conversations.
Making Finances a Family Affair
Successful financial plans are built together. Involving everyone, even young children in age-appropriate ways, transforms financial planning into a shared adventure. Start by setting goals together, like a family vacation or a new home. When everyone knows what you’re working toward, daily budget decisions become easier.
Regular, brief money check-ins keep everyone engaged. The key is creating an environment where talking about money feels natural. You can introduce financial topics at different ages:
- Young children: Start with simple concepts like spending, saving, and giving.
- Elementary-age kids: Teach them about earning money through chores and choosing between wants and needs.
- Teenagers: Discuss budgeting, credit, and basic investing.
- Young adults: Guide them on managing their own finances, understanding taxes, and building credit.
By making finances a family affair, you’re not just managing money today—you’re raising financially confident adults for tomorrow.
Teaching Your Children About Money
One of the greatest gifts you can give your children is financial literacy. This doesn’t require special expertise, just intention and consistency.
For young children, the classic saving, spending, and giving jars are highly effective. This makes abstract concepts concrete. An allowance offers another opportunity to practice real-world money decisions, whether it’s tied to chores or not.
As children become teens, give them responsibility for their own budget for clothes or entertainment. These small, safe learning experiences prepare them for bigger financial decisions. You can even introduce investing concepts by explaining that owning a stock means owning a tiny piece of a company. Watching an investment’s value change teaches patience and long-term thinking.
Everyday moments are learning opportunities, from comparing prices at the grocery store to discussing the budget for a family vacation. These conversations are fundamental to financial planning for young families, as you’re shaping how the next generation will manage their own wealth. More info about Wealth Transfer and Legacy Planning.
Frequently Asked Questions about Family Financial Planning
It’s normal to have questions when navigating financial planning for young families. Here are some common ones, with concise answers to help you feel more prepared.
How much life insurance does a young family really need?
A common rule of thumb is to have life insurance coverage equal to 10 times your annual income, which for young families often means a policy of $1 million to $2 million. This amount helps cover the mortgage, daily expenses, and future goals like college. It’s also crucial to insure a stay-at-home parent to cover the significant costs of childcare and household management their work provides.
Should we save for retirement or our child’s college first?
Financial experts agree: prioritize your retirement savings. Your children can use scholarships, grants, and loans for college, but you cannot borrow for retirement. Securing your own future prevents you from becoming a financial burden on them later. Always contribute enough to your 401(k) to get the full employer match—it’s free money. After that, focus on other retirement accounts like an IRA before aggressively funding college savings.
What is the single most important first step in financial planning for a new family?
While budgeting is vital, the single most important first step is to establish essential legal documents. A will is crucial for naming a guardian for your children and directing how your assets are distributed. Supporting documents like a power of attorney and healthcare proxy ensure your wishes are followed if you’re incapacitated. These documents provide a foundational layer of protection and peace of mind for your family.
Conclusion
The journey of financial planning for young families is about taking thoughtful, consistent steps. By creating a budget, protecting your loved ones with insurance and estate documents, implementing smart saving strategies, and fostering open communication, you build a robust plan for a secure future.
Each of these steps, woven together, brings stability and peace of mind. It’s a long-term journey where consistent effort pays off.
At Acadia Wealth Advisors, we help families in Charlottesville, Richmond, Alexandria, Roanoke, and Lynchburg, VA, steer these exciting times. Our data-driven guidance is designed to help you achieve stable growth, ensure accessible funds, and build multi-generational wealth for your family’s legacy.
Taking proactive steps today lays a strong foundation for tomorrow. Ready to take the next step in your family’s future? We’re here to help you secure it. Take the next step in your family’s future with our Estate Planning services.